
The Complete Overview of Retirement Net Worth
Retirement net worth isn’t just a balance sheet—it’s a reflection of decades of financial behavior. The data reveals that while some retirees enter their golden years with substantial wealth, others face precarious stability. According to the 2022 Federal Reserve report, the median net worth for Americans aged 65–74 stands at approximately $260,000, but this figure is heavily influenced by home equity. Exclude primary residences, and the median drops to around $60,000. The disparity between median and mean (average) figures underscores wealth concentration: the top 10% of retirees hold nearly 50% of total retirement assets. This concentration isn’t accidental; it’s the result of compounding, inheritance, and access to higher-paying jobs. The question of what is average net worth at retirement also hinges on generational differences. Baby Boomers, who benefited from rising home values and employer pensions, entered retirement with significantly higher net worth than Millennials or Gen Xers. For Gen X, the median net worth at retirement is estimated to be around $150,000—lower due to student debt burdens and the 2008 financial crisis. Millennials, still decades from retirement, face an even bleaker outlook unless current trends reverse. The data suggests that without structural changes—like stronger Social Security solvency or expanded pension plans—the retirement wealth gap will persist.Historical Background and Evolution
The concept of retirement as a phase of life funded by personal savings is relatively new. Before the 20th century, most people worked until they physically couldn’t, relying on family or community support. The modern retirement framework emerged in the early 1900s with the introduction of pensions and Social Security in the U.S. and similar systems in Europe. These programs were designed to replace lost wages, but they assumed stable employment and low healthcare costs—assumptions that no longer hold. Over the past 50 years, the definition of what is average net worth at retirement has shifted dramatically. The rise of 401(k) plans in the 1980s replaced defined-benefit pensions, shifting risk from employers to individuals. This change coincided with stagnant wage growth and soaring healthcare expenses, forcing retirees to rely more on personal savings. The result? A system where retirement security depends on market performance, personal discipline, and longevity. Historical data shows that retirees who entered the workforce before 1980 had pensions covering 60–70% of their pre-retirement income; today, that figure is closer to 20–30% for most workers.Core Mechanisms: How It Works
Retirement net worth is the sum of assets minus liabilities at the point of leaving work. Key components include: - Home equity (often the largest asset for retirees). - Retirement accounts (401(k)s, IRAs, defined-benefit pensions). - Investments (stocks, bonds, real estate beyond primary residences). - Debt (mortgages, credit cards, student loans). - Liquid savings (emergency funds, cash reserves). The mechanics of building this net worth revolve around three pillars: saving rate, investment returns, and time. A retiree who saves 15% of their income consistently and earns a 7% annual return on investments will accumulate wealth far faster than someone saving 5% with lower returns. However, market volatility—like the 2008 crash or the 2020 COVID sell-off—can derail even the best-laid plans. The what is average net worth at retirement question thus depends on how well individuals navigate these variables.Key Benefits and Crucial Impact
Understanding retirement net worth isn’t just about numbers—it’s about freedom. A higher net worth at retirement translates to fewer financial constraints, greater flexibility, and reduced stress. Studies show that retirees with robust net worth are more likely to engage in leisure activities, travel, and support family members. The psychological impact is equally significant: financial security in retirement correlates with better mental health and longer lifespans. Yet, the benefits aren’t universal. Retirees with low net worth often face trade-offs—delaying medical care, downsizing homes, or relying on family support—all of which erode quality of life. The impact of retirement net worth extends beyond individuals. Economically, retirees with substantial assets contribute to local economies through spending, while those struggling may drain public resources. Socially, wealth disparities in retirement can deepen generational divides, as older generations with higher net worth pass on more inheritance to their children. The data suggests that what is average net worth at retirement isn’t just a personal metric—it’s a barometer of broader economic and social health."Retirement isn’t an event; it’s a process. The numbers matter, but they’re meaningless without a plan to turn them into a life you want to live." — Jane Bryant Quinn, Personal Finance Journalist
Major Advantages
- Financial independence: Higher net worth reduces reliance on Social Security or part-time work, allowing retirees to pursue passions.
- Healthcare flexibility: Wealthier retirees can afford private insurance or premium healthcare services without sacrificing other needs.
- Legacy planning: Those with substantial assets can leave inheritances or donate to causes, shaping their financial legacy.
- Longevity security: Stronger net worth correlates with better access to long-term care and age-friendly housing.
- Market resilience: Diversified portfolios weather economic downturns better, preserving wealth over time.
- Psychological well-being: Financial confidence in retirement is linked to lower stress and higher life satisfaction.
Comparative Analysis
| Metric | U.S. (Median) | Europe (Median) |
|---|---|---|
| Net worth at retirement (65–74) | $260,000 (home equity included) | €150,000–€200,000 (varies by country) |
| Primary driver of wealth | Home equity (60%), retirement accounts (25%) | Pensions (40%), home equity (30%) |
| Top 10% threshold | $2 million+ | €1 million+ (Nordic countries higher) |
| Biggest risk factor | Healthcare costs, longevity | Inflation, pension sustainability |
| Early retirement feasibility | Possible with $1M+ (FIRE movement) | Rare due to socialized systems |
Future Trends and Innovations
The retirement landscape is evolving rapidly. Automation and AI are reshaping job markets, potentially extending working years or reducing traditional career paths. Meanwhile, climate change and urbanization are altering where people retire—with coastal cities facing depopulation as retirees seek affordable, low-risk locations. Technological advancements, like robo-advisors and fractional investing, are making it easier for average earners to build retirement wealth, but these tools also introduce new risks, such as algorithmic mismanagement of portfolios. Another critical trend is the rise of what is average net worth at retirement as a generational issue. Millennials and Gen Z face higher student debt, stagnant wages, and housing crises, suggesting that future retirement net worth may decline unless policy interventions—like expanded Social Security or student debt relief—emerge. Innovations in longevity medicine could extend retirement years, increasing the need for larger nest eggs. The future of retirement net worth will likely depend on how well individuals adapt to these changes—and whether societal structures keep pace.
Conclusion
The question of what is average net worth at retirement has no single answer, but the data provides a roadmap. For most Americans, the median figure is a starting point, not a target. The real conversation should focus on personalization: adjusting savings rates, diversifying income streams, and planning for longevity. Retirement isn’t about hitting a specific number—it’s about building a financial foundation that aligns with individual goals, whether that means early freedom, luxury travel, or simply avoiding hardship. The disparities in retirement net worth highlight deeper systemic issues—inequality, healthcare costs, and the erosion of employer-sponsored pensions. Addressing these challenges requires both personal discipline and policy changes. For now, the best approach remains proactive: monitor trends, diversify assets, and redefine what "enough" means. In an era of uncertainty, the most secure retirees won’t be those with the highest net worth—but those who understand how to make their wealth work for them.Comprehensive FAQs
Q: What is the median net worth for retirees in the U.S.?
The Federal Reserve’s latest data suggests the median net worth for Americans aged 65–74 is around $260,000, though this includes home equity. Excluding primary residences, the median drops to approximately $60,000.
Q: How does homeownership affect retirement net worth?
Homeownership is the single largest asset for most retirees, accounting for about 60% of median net worth. Owning a paid-off home significantly boosts retirement security, while renters or those with mortgages face higher financial vulnerability.
Q: Can someone retire comfortably with $500,000?
It depends on location and spending habits. In low-cost areas, $500,000 may suffice for 20–30 years using the 4% rule, but in high-cost regions, it could deplete faster. Healthcare costs and market downturns are wildcards that can disrupt even well-funded plans.
Q: Why is retirement net worth lower for Gen X than Boomers?
Gen X entered the workforce during economic downturns (2008 crisis), faced stagnant wages, and carried higher student debt. Unlike Boomers, who benefited from pensions and rising home values, Gen X relied more on 401(k)s, which underperformed during critical years.
Q: How does inflation impact retirement net worth?
Inflation erodes purchasing power, meaning a retiree’s $260,000 net worth today may buy less in 10 years. Strategies like TIPS (Treasury Inflation-Protected Securities) or annuities can mitigate this risk, but retirees must account for long-term inflation trends in their withdrawal plans.
Q: What’s the difference between median and average net worth?
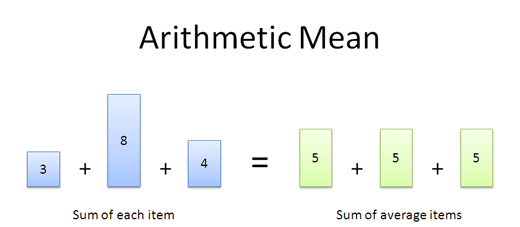
The median is the middle value when all retirees’ net worth is ranked, while the average (mean) is the total net worth divided by the number of retirees. The average is skewed higher by ultra-wealthy retirees, making the median a more realistic benchmark for most people.
Q: Can I retire early with a net worth below $1 million?
Yes, but it requires extreme frugality and a low-cost lifestyle. The "FIRE" (Financial Independence, Retire Early) movement demonstrates that retirees can live on $25,000–$40,000/year with $500,000–$800,000, but this is only feasible in low-cost areas or with significant income from passive sources.
Q: How do healthcare costs factor into retirement net worth?
Healthcare is the biggest wildcard. Fidelity estimates a 65-year-old couple needs $315,000 for healthcare in retirement, but this varies by region. Medicare doesn’t cover everything, so retirees must budget for supplements, long-term care, and prescription drugs—all of which can deplete net worth quickly.
Q: What’s the safest way to preserve retirement net worth?
Diversification is key: a mix of stocks (for growth), bonds (for stability), and liquid savings (for emergencies). Annuities can provide guaranteed income, while avoiding sequence-of-returns risk (poor market timing early in retirement) is critical. Regular portfolio reviews help adjust for inflation and market changes.
Q: Does Social Security count toward retirement net worth?
No, Social Security benefits are an income stream, not an asset. They’re calculated based on earnings history and life expectancy but don’t contribute to net worth figures. However, they’re often a retiree’s largest income source, so planning around them is essential.
