
The Complete Overview of the Average Net Worth of a 60-Year-Old
The average net worth of a 60-year-old is a product of three interlocking forces: the economic conditions they’ve navigated, the financial decisions they’ve made, and the policies that shaped their opportunities. For the Silent Generation, wealth accumulation was often tied to unionized labor, employer pensions, and a housing market where home values appreciated steadily. By contrast, Baby Boomers—now in their late 50s and early 60s—entered the workforce during the stagflation of the 1970s, only to see their peak earning years coincide with the dot-com bubble and the Great Recession. Millennials, now approaching 40, will inherit a different landscape, where gig work and student loans redefine what it means to build wealth by 60. Regional disparities further distort the picture. In high-cost coastal cities, a 60-year-old’s net worth may appear robust on paper—driven by inflated home values—but liquid assets and retirement savings tell a different story. In Rust Belt cities or rural areas, where homeownership rates lag and wages have stagnated, the average net worth of a 60-year-old can be a fraction of national medians. Even within states, urban-suburban divides create stark contrasts: a 60-year-old in Austin might have a portfolio swollen by tech equity, while their peer in nearby rural counties relies on Social Security as their primary income stream.Historical Background and Evolution
The trajectory of the average net worth for someone turning 60 has been shaped by three major economic eras. The post-WWII boom saw wealth accumulate through employer pensions and defined benefit plans, with homeownership acting as both a stable asset and a forced savings mechanism. By the 1980s, the shift to defined contribution plans—like 401(k)s—meant individuals bore more risk, and the average net worth of a 60-year-old became increasingly tied to market performance. The 2008 crisis then reset expectations: those nearing retirement saw portfolios slashed, while younger workers faced prolonged unemployment, delaying their own wealth-building timelines. Today, the average net worth of a 60-year-old is also a reflection of demographic shifts. The decline of manufacturing jobs, the rise of service-sector employment, and the gig economy’s growth have created a bifurcated landscape. Professionals in finance, tech, or healthcare often see their net worth surge in their 50s, while those in trades or low-wage service roles may plateau—or even decline—after decades of work. The data reveals another layer: women, who have historically earned less and faced career interruptions, typically enter their 60s with net worth figures that are 30–40% lower than their male counterparts, even after controlling for hours worked.Core Mechanisms: How It Works
The mechanics behind the average net worth of a 60-year-old are rooted in three pillars: asset accumulation, debt management, and timing. Home equity is the most significant driver for most, accounting for nearly 60% of total net worth in this age group. Those who bought homes in the 1980s or 1990s—when prices were lower and mortgage terms more favorable—benefit from decades of appreciation, even if their incomes haven’t kept pace. Retirement accounts, meanwhile, act as both a savings vehicle and a market-dependent asset class. Someone who maxed out a 401(k) in the 2000s saw those balances swell during the tech boom, only to shrink during the 2008 downturn, with partial recovery in the subsequent bull market. Debt plays a paradoxical role. For many, a mortgage is a forced savings tool, but for others—particularly those who took on student loans later in life to pursue advanced degrees or care for aging parents—debt can erode net worth. The average net worth of a 60-year-old in 2024 is also influenced by unexpected liabilities, such as medical expenses or long-term care costs, which can decimate savings for those without robust insurance. Finally, timing matters: someone who retired in 2019 benefited from a strong stock market, while those forced into early retirement during the pandemic saw their portfolios take a hit, with limited time to recover.Key Benefits and Crucial Impact
Understanding the average net worth of a 60-year-old isn’t just an academic exercise—it’s a lens into the health of the broader economy. When this cohort’s wealth grows, it signals robust job markets, rising home values, and effective retirement planning. When it stagnates or declines, it points to wage suppression, healthcare costs spiraling out of control, or a failure to pass wealth across generations. For policymakers, these figures inform decisions on Social Security solvency, tax incentives for retirement savings, and housing affordability. For individuals, they serve as a benchmark: a 60-year-old with a net worth below the median may need to adjust expectations for retirement, while those above it can explore legacy planning or early retirement strategies. The psychological impact is equally significant. For many, crossing the 60-year threshold is a moment of reckoning. Those who’ve built substantial wealth often feel a sense of relief, knowing they’ve weathered economic storms and can now focus on philanthropy or part-time passions. Others experience a quiet panic, realizing their savings won’t stretch as far as they’d hoped. The average net worth of a 60-year-old isn’t just a number—it’s a measure of resilience, opportunity, and the invisible rules that have shaped a lifetime of financial decisions."By the time you’re 60, your net worth isn’t just about what you’ve saved—it’s about what the system allowed you to accumulate. And for too many, the system was rigged against them from the start." — Darrick Hamilton, economist and professor at The New School
Major Advantages
- Leveraged home equity: For most 60-year-olds, their primary residence represents the largest asset, with decades of mortgage payments effectively acting as forced savings.
- Retirement account growth: Those who contributed consistently to 401(k)s, IRAs, or pensions benefit from compounding, even if market volatility has tested their balances.
- Reduced discretionary spending: With children grown and fewer major expenses, many in this age group can redirect income toward savings or debt repayment.
- Social Security optimization: Those who’ve worked for 30+ years can claim benefits at full retirement age or delay for higher payouts, creating a flexible income stream.
- Generational wealth transfer: For those who’ve inherited assets or received gifts, this period often marks the peak of intergenerational wealth accumulation.

Comparative Analysis
| Metric | Average Net Worth of a 60-Year-Old (2024) |
|---|---|
| Median Net Worth (All Races) | $260,000 (Federal Reserve, 2022) |
| Mean Net Worth (All Races) | $1.2 million (skewed by top 10%) |
| Median Net Worth (White Households) | $320,000 (vs. $23,000 for Black households) |
| Primary Asset Composition | Home equity (60%), retirement accounts (25%), other investments (15%) |
Future Trends and Innovations
The average net worth of a 60-year-old in the coming decade will be shaped by three emerging trends. First, the rise of longevity economics means more people will need their savings to last 30+ years in retirement, pushing demand for annuities and hybrid retirement products. Second, the gig economy’s expansion may lead to a new class of 60-year-olds with non-traditional income streams—consulting, freelance work, or asset rental—but also greater financial instability. Finally, climate-related risks, from property insurance hikes to supply chain disruptions, could erode net worth for those living in high-exposure areas, particularly in coastal or wildfire-prone regions. Technological innovation may also reshape wealth accumulation. Robo-advisors and AI-driven financial planning tools could help those nearing retirement optimize their portfolios, but they may also deepen inequalities if access remains limited to higher-income earners. Meanwhile, the debate over student debt cancellation could indirectly boost the net worth of older Americans who’ve been burdened by loans taken out for their own educations or those of their children. As these forces interact, the traditional definition of the average net worth of a 60-year-old may evolve—less a static number, and more a dynamic reflection of how people navigate an economy in flux.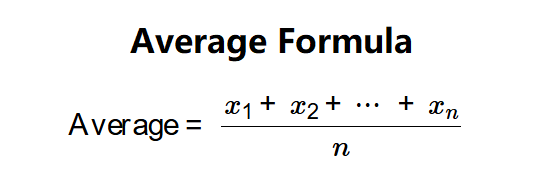
Conclusion
The average net worth of a 60-year-old is more than a statistical footnote—it’s a mirror held up to the economic realities of an entire generation. It reveals the scars of past recessions, the benefits of housing booms, and the quiet victories of disciplined saving. Yet it also exposes the fractures in the system: the racial wealth gap that persists despite decades of progress, the precarity of those who’ve worked in non-unionized fields, and the growing divide between those who’ve benefited from asset appreciation and those who’ve been left behind. For individuals, these numbers serve as both a report card and a roadmap. Those who’ve thrived often did so through a mix of luck, strategy, and adaptability. Those who’ve struggled may still have time to course-correct, but the window is narrowing. The conversation around the average net worth of a 60-year-old must move beyond the numbers themselves. It should ask harder questions: Why do Black and Latino households enter this stage of life with so much less? How can policies ensure that future generations don’t face the same disparities? And what does it say about our economy when a person’s financial security at 60 hinges so heavily on the zip code they were born into? The answers will determine not just the wealth of individuals, but the stability of societies.Comprehensive FAQs
Q: How does the average net worth of a 60-year-old compare to previous generations?
The average net worth of a 60-year-old today is higher in nominal terms than for previous generations, but when adjusted for inflation and housing costs, the gains are modest. Silent Generation retirees often had stronger pension benefits and lower healthcare costs, while Boomers face higher education expenses for their children and longer retirement horizons. The key difference is the shift from defined benefit to defined contribution plans, which has made retirement security more dependent on individual market performance.
Q: What’s the biggest factor affecting whether a 60-year-old has above-average net worth?
Homeownership status is the single largest determinant. Those who own their homes outright or have significant equity benefit from forced savings and asset appreciation. The next biggest factors are consistent retirement account contributions, especially during bull markets, and inheritance or gifts from family. Career stability—particularly in high-paying fields like healthcare, law, or tech—also plays a critical role.
Q: Can a 60-year-old still increase their net worth significantly?
Yes, but the opportunities are more limited than in earlier decades. Strategies include downsizing to a lower-cost home, taking on part-time work or consulting gigs, or optimizing Social Security claims. For those with liquid assets, investing in dividend stocks or annuities can provide steady income. However, the window for aggressive wealth-building is narrower—most focus shifts to preservation and legacy planning.
Q: How does student debt impact the average net worth of a 60-year-old?
Student debt is increasingly a burden for older Americans, either from their own educations or from helping children repay loans. For those who took out loans later in life—such as for nursing degrees or MBAs—the debt can erode net worth, especially if retirement savings haven’t kept pace. Data suggests that households with student debt in their 60s have median net worth figures that are 20–30% lower than those without such liabilities.
Q: What’s the most common mistake 60-year-olds make with their finances?
The most frequent misstep is underestimating healthcare costs in retirement. Many assume Medicare will cover most expenses, but long-term care, prescription drugs, and dental/vision costs can quickly deplete savings. Another common error is failing to diversify investments as they approach retirement—holding too much in employer stock or other illiquid assets. Finally, some neglect to adjust their retirement plans after major life changes, like divorce or the death of a spouse.
Q: How does the average net worth of a 60-year-old vary by state?
There’s significant variation. States with high home values—like California, Massachusetts, and Washington—see higher median net worth figures, but cost of living eats into disposable income. Conversely, states with lower housing costs—such as Mississippi or West Virginia—often have lower median net worths, though retirees may stretch their savings further. Urban areas within states (e.g., New York City vs. upstate New York) can show even wider disparities, with coastal cities typically favoring wealthier retirees.
