
Common Myths About the Average Net Worth for a 33-Year-Old
The first misconception is that average net worth for 33-year-olds is a reliable benchmark for personal success. In truth, these figures are statistical averages, not aspirational targets. A 33-year-old with $250,000 in assets might be struggling with student debt or a mortgage, while someone with $50,000 could be debt-free with a fully funded emergency fund. Context matters: a New Yorker’s $150,000 net worth might cover a tiny apartment and a modest 401(k), while a Midwesterner’s $120,000 could include a paid-off home and no loans. Another persistent myth is that age alone determines wealth. The data shows that financial habits matter more than birth year. A 33-year-old who started investing at 25 with consistent contributions will outpace a 40-year-old who only began saving last year. Yet, narratives about "millennial struggles" often overlook the role of timing, luck, and structural advantages—like inheriting wealth or entering a booming industry early. For example, someone who bought a home in 2012 likely saw equity gains dwarfing renters’ savings, even if their incomes were similar. The third myth frames average net worth for 33-year-olds as a fixed milestone. In reality, it’s a moving target influenced by economic shocks. The 2008 financial crisis left a generation with stagnant wages and delayed homebuying, while the 2020 pandemic accelerated wealth gaps as stock markets surged while service workers faced layoffs. A 33-year-old in 2024 isn’t comparing themselves to peers from 2014—they’re navigating an economy where rent is up 50% in a decade, student debt is a $1.7 trillion albatross, and inflation eats into every dollar saved.Myth 1: "Most 33-year-olds are millionaires."
This claim stems from headlines about tech CEOs or celebrity earnings, but the reality is far bleaker. According to the Federal Reserve’s 2022 Survey of Consumer Finances, only 0.3% of Americans under 35 have a net worth exceeding $1 million. Even among the top 10% of earners, the average net worth for a 33-year-old in the U.S. sits around $300,000–$500,000, with the majority of that tied to home equity or retirement accounts. The rest? A mix of savings, vehicles, and—for many—significant debt. The confusion arises because wealth isn’t distributed evenly. A 2023 analysis by the Brookings Institution found that 90% of wealth gains in the past decade went to the top 10% of households. For the average 33-year-old, wealth accumulation is a slow grind: saving $500/month at a 7% return yields just $100,000 by age 33. Add in student loans, childcare costs, or medical debt, and the picture shifts from "millionaire" to "just getting by."Myth 2: "If you’re not a homeowner by 33, you’ll never recover."
Homeownership is often treated as the cornerstone of wealth-building, but the data tells a different story. While homeowners do tend to have higher net worths—median $255,000 vs. $6,300 for renters—it’s not the house itself that builds wealth; it’s equity and market timing. A 33-year-old who bought in 2020 at peak prices may have negative equity today, while a renter who invested that down payment in index funds could be ahead. Moreover, location dictates everything. In San Francisco or New York, a $600,000 home might leave little room for savings, whereas in Detroit or Kansas City, that same price buys equity and appreciating property. The average net worth for 33-year-olds in rural areas often exceeds urban peers because housing costs are lower, not because they’re savvier investors. For many, renting isn’t a failure—it’s a tactical choice to prioritize liquid assets over illiquid real estate.Myth 3: "Your net worth should be 2x your annual income by 33."
This rule of thumb—popularized by financial gurus—ignores the fact that income and net worth are decoupled for most people. A 33-year-old earning $150,000/year might have a net worth of $80,000 (below the "2x" target), while a peer earning $80,000 could have $120,000 due to frugality, inheritances, or low living costs. The rule assumes consistent savings rates and no major expenses, which is rare for someone juggling student loans, childcare, or eldercare. What’s more, the average net worth for 33-year-olds varies wildly by field. A software engineer in Austin might hit the 2x mark, but a social worker in Chicago won’t—unless they’ve made deliberate trade-offs (e.g., living with family, side hustles). The truth? Net worth at 33 is less about income and more about leverage—how you’ve used credit, investments, and time to amplify earnings.
What Holds Up to Scrutiny
The most reliable data on average net worth for 33-year-olds comes from longitudinal studies tracking wealth accumulation over time. The Federal Reserve’s SCF and Urban Institute reports consistently show that by age 33: - Median net worth in the U.S. is $97,000 (2022 data). - Mean net worth jumps to $436,000, but this is skewed by the ultra-wealthy. - Homeownership status is the single biggest predictor of wealth at this age. What’s often overlooked is the role of inherited wealth. A 2021 Pew Research study found that 20% of 33-year-olds received an inheritance or gift of $10,000+, which can catapult net worth into higher tiers. For those without family support, the path to wealth is steeper—requiring high savings rates, asset appreciation, or career windfalls."Net worth at 33 isn’t a measure of success—it’s a snapshot of opportunity hoarded or squandered. The real question isn’t how much you have, but how much you can control." — Rachel Schneider, economist at the St. Louis Fed
| Common Belief | What the Evidence Says |
|---|---|
| Most 33-year-olds have $200K+ in net worth. | Only the top 10% exceed this; median is $97K. |
| Renting by 33 means financial failure. | Renters’ net worth grows faster when they invest rent savings vs. leveraging home equity. |
| Your net worth should double your income by 33. | This ignores debt, location costs, and inherited advantages. |
Why the Confusion Persists
Part of the problem is selective storytelling. Financial media loves featuring outliers—the 33-year-old hedge fund manager or influencer—while ignoring the 90% who are still climbing. Even academic studies often focus on cross-sectional data (snapshots at one time), which can’t capture how wealth builds over decades. A 33-year-old’s net worth today may look modest, but if they’ve been consistently saving and investing, it could grow exponentially by 45. Another factor is the myth of meritocracy. Many assume that wealth at 33 is earned, not inherited or luck-based. Yet, 60% of wealth in the U.S. comes from inheritance, and early access to capital (e.g., family loans, trust funds) gives some a 10-year head start. The average net worth for 33-year-olds reflects these disparities—white households start with $10,000 more in assets at birth than Black or Hispanic peers, a gap that widens with age.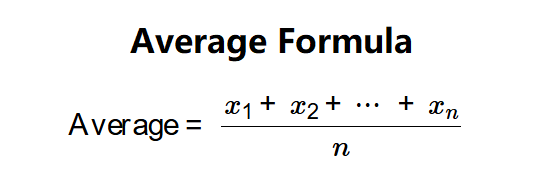
Conclusion
The average net worth for a 33-year-old isn’t a failure metric or a success badge—it’s a data point in a larger story. For some, it’s the result of discipline, luck, and timing; for others, it’s a reflection of systemic barriers. What matters more than the number itself is what it tells you about your own trajectory. Are you saving aggressively? Leveraging assets? Or stuck in a cycle of debt and stagnation? The good news? Wealth at 33 is malleable. A side hustle, a career pivot, or aggressive debt payoff can reshape the narrative. The bad news? The system is rigged. Those who entered the workforce post-2008 face lower wages, higher costs, and fewer safety nets than previous generations. The average net worth for 33-year-olds in 2024 will likely be lower than in 2014, adjusted for inflation—a reminder that economic progress isn’t linear.Comprehensive FAQs
Q: How does the average net worth for a 33-year-old compare globally?
The U.S. median sits at $97,000, while the UK averages £120,000 (~$150K), and Canada reports $110,000 CAD (~$80K USD). Nordic countries see higher figures due to strong social safety nets, while developing nations (e.g., India, Brazil) report medians below $5,000. The gap reflects wage disparities, housing costs, and financial systems—not just effort.
Q: Should I aim for the average net worth for a 33-year-old, or is that too low?
The average is a median, not a target. If your goal is financial security, aim for 3–5x your annual expenses in net worth by 33. For example, if you spend $4,000/month, shoot for $144,000–$240,000. The average is just a reference point—your context (debt, family, location) dictates what’s "enough."
Q: Does student debt significantly lower the average net worth for 33-year-olds?
Absolutely. The Federal Reserve estimates that 40% of 33-year-olds with bachelor’s degrees have student loans, dragging median net worth down by $30,000–$50,000. Those with advanced degrees fare worse—median net worth drops by $70,000 when accounting for grad school debt. The trade-off between earning potential and debt burden is the biggest wealth killer for this age group.
Q: Can I catch up if my net worth at 33 is below average?
Yes, but it requires aggressive action. Focus on:
- Eliminating high-interest debt (credit cards, payday loans).
- Maximizing tax-advantaged accounts (401(k), IRA).
- Increasing income via side hustles or skill-building.
Q: How does marriage or children affect the average net worth for a 33-year-old?
Married couples typically see higher median net worth (~$120K vs. $70K for singles), but this masks unequal labor dynamics. Women’s net worth drops 30% after childbirth due to career interruptions, while men’s rises. Single parents fare worse—median net worth is $20K lower than childless peers. The data isn’t about relationships; it’s about who bears the financial and caregiving burden.
Q: Are there industries where the average net worth for 33-year-olds is significantly higher?
Yes. Fields with high earning potential, equity compensation, or asset ownership skew wealth upward:
- Tech/Engineering: Median net worth $250K+ due to stock options.
- Healthcare (Specialists): $300K–$500K from bonuses and low student debt.
- Real Estate/Finance: $400K+ if leveraging investments early.
Q: What’s the biggest mistake people make when tracking their net worth at 33?
Ignoring illiquid assets (e.g., home equity, retirement accounts) and overvaluing liquidity. Many panic if their checking account is low but ignore that their 401(k) or home could be worth 10x more. Others compare themselves to peers in different life stages—e.g., a 33-year-old CEO vs. a 33-year-old parent. The key is tracking trends, not absolute numbers. If your net worth is growing 5–10% annually, you’re likely on track—even if it’s below the average.
