
Where It All Began
The roots of the modern "average net worth of upper class American" stretch back to the late 19th century, when industrialists like Rockefeller and Carnegie didn’t just build fortunes—they built systems. Their wealth wasn’t just cash; it was oil refineries, railroads, and the political connections to protect it. The upper class of that era understood something critical: wealth wasn’t about income. It was about control. By the 1920s, the top 1% held nearly 40% of all wealth—a figure that would only grow when the New Deal temporarily redistributed it. But even then, the upper class adapted. They shifted from raw industry to finance, from manufacturing to real estate, and by the 1980s, they had weaponized debt. The Reagan era didn’t just cut taxes—it rewrote the rules of wealth accumulation. Deregulation allowed banks to gamble with deposits, private equity to strip-mine public companies, and hedge funds to bet against entire economies. The "average net worth of upper class American" in the 1990s wasn’t just higher; it was exponential. The dot-com boom and bust proved the point: while tech millionaires burned out, the old money—those with diversified portfolios, offshore accounts, and family trusts—weathered the storm. They had learned the lesson of the Gilded Age: wealth is power, and power compounds.The Early Signs
By the mid-2000s, the signs were impossible to ignore. The "average net worth of upper class American" had stopped being a matter of public record and started being a matter of private ledgers. The richest 0.1%—those with net worths exceeding $20 million—held more wealth than the entire bottom 90%. But the real shift wasn’t in the numbers. It was in the strategies. The upper class stopped relying on salaries. They moved into passive income: dividends, capital gains, and the quiet appreciation of assets they never had to sell. The financial crisis of 2008 exposed the fragility of the middle class but confirmed the resilience of the upper class. While home values evaporated for millions, the "average net worth of upper class American" in the top 1% actually increased by 11% between 2007 and 2010. How? By owning the banks. By shorting the market. By hoarding cash while everyone else borrowed. The crisis wasn’t a setback—it was a reset. And the upper class came out stronger.The Turning Point
The moment the "average net worth of upper class American" became a political battleground was 2013, when the Occupy Wall Street protests finally forced a reckoning. The 99% vs. the 1% wasn’t just a slogan—it was a financial fact. That year, the Federal Reserve released data showing that the top 10% of households owned 76% of all stocks, 84% of taxable bonds, and 89% of nonhome financial assets. The upper class wasn’t just rich. They owned the tools to get richer. What changed wasn’t just the numbers. It was the speed. The upper class had always been patient, but by the 2010s, their wealth accumulation had become automated. Algorithmic trading, private credit markets, and the rise of alternative investments (like art, wine, and even Bitcoin) meant that money could be made—and hidden—without ever touching a bank account. The "average net worth of upper class American" wasn’t just growing; it was multiplied by new technologies."Wealth isn’t just money. It’s the ability to make money while you sleep." — A former Goldman Sachs partner, 2015The final nail in the coffin came with the 2017 tax cuts, which slashed capital gains taxes and allowed the upper class to lock in their wealth like never before. The result? By 2020, the top 1% held $41.5 trillion in wealth—more than the entire GDP of Germany. The "average net worth of upper class American" wasn’t just higher than ever. It was untethered from reality.

The Build-Up, Year by Year
| Period | What Happened |
|---|---|
| 1980s | Reaganomics deregulates finance. The upper class shifts from industrial wealth to financial assets. The "average net worth of upper class American" begins its modern ascent. |
| 2000s | Dot-com bubble bursts, but the upper class pivots to private equity and hedge funds. The financial crisis of 2008 wipes out middle-class wealth—while the upper class’s net worth increases. |
| 2010s | Quantitative easing floods markets with cheap money. The upper class loads up on stocks, real estate, and alternative assets. The "average net worth of upper class American" hits new highs. |
| 2020s | Pandemic wealth effect: while millions lose jobs, the upper class sees portfolio gains. Bitcoin, NFTs, and SPACs become new wealth accumulation tools. |
Lessons From the Journey
- Wealth isn’t static. The upper class doesn’t just earn money—they reinvest it in ways that generate more money.
- Leverage is power. Debt works differently for the rich: they borrow against assets, not against income.
- Taxes are optional. The upper class uses trusts, offshore accounts, and legal loopholes to minimize exposure.
- Crises are opportunities. While others panic, the upper class buys assets at fire-sale prices.
Where Things Stand Today
As of 2024, the "average net worth of upper class American"—defined as the top 5% of households—exceeds $4 million, according to the latest Federal Reserve data. But the real story isn’t the average. It’s the distribution. The top 0.1% (net worth over $20 million) holds $20 trillion—more than the entire GDP of India. What’s changed in the last decade isn’t just the size of their wealth. It’s the speed at which it grows. The upper class today operates in a parallel economy. They don’t use traditional banks. They use private credit lines, family offices, and alternative investment platforms. Their wealth isn’t just in stocks—it’s in private jets, vineyards, and even space assets. And while the middle class struggles with student debt and stagnant wages, the upper class has weaponized inflation: borrowing cheap, investing in appreciating assets, and then paying back with devalued currency.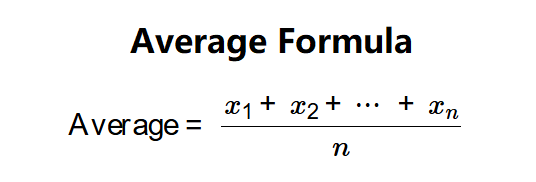
Conclusion
The "average net worth of upper class American" isn’t just a number. It’s a system. And that system has been perfected over centuries. The upper class didn’t just get lucky. They engineered luck. They turned crises into windfalls, regulations into opportunities, and markets into personal ATMs. The question now isn’t just "How rich are the rich?" It’s "How do we change the rules?" Because until then, the "average net worth of upper class American" will keep climbing—while everyone else watches from below.Comprehensive FAQs
Q: What exactly defines the "upper class" in America?
The upper class is typically defined by net worth, not income. The top 1% holds around $10 million+, while the top 5% (often considered the upper class) has a net worth exceeding $1.5 million. However, the real dividing line is liquidity and asset control—the ability to deploy wealth without touching traditional markets.
Q: How does the upper class’s net worth compare to the middle class?
As of 2024, the median net worth for a middle-class household (top 20%) is $250,000, while the "average net worth of upper class American" (top 5%) is over $4 million. The gap isn’t just about money—it’s about generational wealth, tax advantages, and access to exclusive investment opportunities.
Q: Do most upper-class Americans inherit their wealth?
Studies suggest that 60-70% of ultra-high-net-worth individuals (those with $30M+) inherit at least some of their wealth. However, even those who "self-made" their fortunes often leverage inherited connections—family networks, old-money social capital, or trust funds that provide seed capital.
Q: How do the ultra-rich protect their wealth from taxes?
The upper class uses a mix of legal strategies: offshore trusts (in places like the Cayman Islands or Switzerland), private annuities, charitable remainder trusts, and carried interest loopholes (common in private equity). Some also structure their wealth in family limited partnerships (FLPs), which allow them to transfer assets at discounted values.
Q: Is the upper class’s wealth growing faster than the economy?
Yes. Since the 2008 financial crisis, the "average net worth of upper class American" has grown faster than GDP. While the overall economy has expanded by ~50% in real terms since 2009, the top 1%’s wealth has doubled—thanks to asset appreciation, tax cuts, and the compounding effects of financial engineering.
Q: What’s the biggest threat to the upper class’s wealth?
While no system is permanent, the biggest existential threat isn’t economic downturns—it’s political backlash. Rising wealth inequality has led to calls for wealth taxes, inheritance caps, and stricter regulations on private markets. The upper class’s response? Lobbying, political donations, and offshore diversification to ensure their wealth remains untouchable.
