
The Complete Overview of What Is the Average Net Worth of American Citizen
The Federal Reserve’s triennial Survey of Consumer Finances remains the gold standard for answering what is the average net worth of American citizen, but interpreting its findings requires caution. The 2022 report, released in 2023, showed that the mean net worth for U.S. households hit $1,066,000—a figure that would seem robust if not for the fact that it’s dragged upward by the ultra-wealthy. The median, at $120,400, paints a far more representative picture of the typical American’s financial standing. This disconnect highlights a fundamental truth: wealth in the U.S. is not normally distributed. It’s lopsided, with the top 10% holding nearly 70% of all liquid assets. Even these figures mask deeper realities. The Fed’s data excludes the bottom 10% of households—those with negative or near-zero net worth—because their financial positions distort the averages. When you factor in student debt, medical expenses, and stagnant wages, the picture becomes clearer: for most Americans, building wealth is a slow, precarious process. The average net worth of a household headed by someone under 35 is just $12,300, while those aged 65-74 see it balloon to $1,217,000. This isn’t just generational wealth; it’s proof that time, access to capital, and structural advantages determine who thrives financially.Historical Background and Evolution
The modern understanding of what is the average net worth of American citizen emerged in the 1980s, when the Federal Reserve began publishing its Survey of Consumer Finances. Before then, wealth data was patchy, relying on tax records or spotty census estimates. The 1989 survey marked a turning point, revealing that the average net worth had doubled since the 1970s—partly due to the stock market boom of the 1980s and deregulation that allowed financial assets to grow unchecked. Yet even then, the median net worth trailed far behind the mean, signaling early signs of inequality. The 2000s brought dramatic shifts. The dot-com bubble burst in 2000, followed by the Great Recession of 2008, which wiped out trillions in household wealth. By 2010, the median net worth had plunged to $77,300, a 37% drop from 2007. The recovery that followed was uneven: while the top 1% saw their net worth surge post-2009, the bottom 90% remained mired in stagnation. The pandemic-era rebound of 2021–2022—fueled by stimulus checks, remote work, and a roaring stock market—pushed the average net worth to record highs, but the median grew at a glacial pace. This divergence isn’t accidental; it’s the result of policies that favor asset appreciation over wage growth.Core Mechanisms: How It Works
Net worth is the sum of all assets minus liabilities, but its calculation varies wildly depending on who you ask. For the Federal Reserve, assets include primary residences, retirement accounts, stocks, and business equity, while liabilities cover mortgages, student loans, and credit card debt. The problem? Not all assets are liquid. A home’s value counts toward net worth, but selling it to access cash isn’t always feasible. Meanwhile, retirement accounts like 401(k)s are included, even though they’re locked until age 59½. This rigidity means the net worth figures we see are static snapshots, not real-time measures of financial health. The mechanics of wealth accumulation reveal why the average and median diverge so sharply. The top 1% derive the bulk of their net worth from financial assets—stocks, bonds, and business ownership—while the middle class relies on home equity and retirement savings. Inheritance plays a disproportionate role: the top 10% of households receive 90% of all intergenerational wealth transfers. For the bottom 40%, debt—especially student loans—often outweighs assets, dragging their net worth into negative territory. This isn’t just about spending habits; it’s about access to the tools that build wealth over time.Key Benefits and Crucial Impact
Understanding what is the average net worth of American citizen isn’t just academic—it’s a lens into economic mobility. When the average rises but the median doesn’t, it suggests that wealth creation is becoming more exclusive. For policymakers, these numbers are a warning: if the middle class’s financial security erodes, consumer spending—70% of the U.S. economy—will follow. For individuals, the data serves as a reality check. A young professional in Chicago might assume their net worth is on par with national averages, only to discover they’re far below the median for their age group. The gap between perception and reality is where financial stress begins. The impact extends beyond personal finance. Wealth disparities influence political power, education quality, and even life expectancy. A 2021 study by the Brookings Institution found that counties where the median net worth is below $100,000 have higher rates of chronic illness and lower life expectancy. The connection between financial health and physical well-being is undeniable. When a family’s net worth is precarious, every unexpected expense—like a car repair or medical bill—becomes a crisis. The average net worth figures we see in headlines are more than numbers; they’re a measure of resilience in the face of an uncertain future."Wealth isn’t just about money. It’s about the options money buys—options like security, mobility, and opportunity. When those options shrink for an entire generation, that’s not just an economic problem. It’s a societal one." — Raghuram Rajan, Former Governor of the Reserve Bank of India
Major Advantages
- Policy benchmarking: Net worth data helps governments design tax policies, housing initiatives, and education reforms that address inequality.
- Consumer behavior insights: Brands and financial institutions use these figures to tailor products—from mortgages to retirement plans—to different demographic segments.
- Generational planning: Families can compare their net worth against age-adjusted averages to assess whether they’re on track for retirement or college savings.
- Investment strategy: High-net-worth individuals rely on these trends to diversify portfolios, while middle-class investors use them to gauge market risks.
- Advocacy tool: Nonprofits and labor unions cite net worth disparities to push for wage growth, student debt relief, and wealth-building programs.
- Global comparisons: Understanding U.S. net worth trends helps economists assess America’s competitiveness against nations like Canada or Germany, where wealth is more evenly distributed.

Comparative Analysis
| Metric | U.S. (2022) |
|---|---|
| Mean (average) net worth | $1,066,000 (Federal Reserve) |
| Median net worth | $120,400 (Federal Reserve) |
| Top 10% net worth threshold | $1,180,000+ (Pew Research) |
| Bottom 50% net worth median | $13,900 (Federal Reserve) |
| White household net worth | $188,200 (median) |
| Black household net worth | $24,100 (median) |
Future Trends and Innovations
The next decade will likely see what is the average net worth of American citizen shaped by three major forces: technology, policy shifts, and demographic changes. Artificial intelligence and algorithmic trading could further concentrate wealth in the hands of those who control capital, while gig economy platforms may offer new pathways for the unbanked to build assets. On the policy front, proposals like a federal wealth tax or expanded child tax credits could either accelerate inequality or narrow the gap—depending on implementation. Demographically, the aging of the Baby Boomer generation will transfer trillions in wealth to younger cohorts, but only if inheritance patterns shift away from the current top-heavy distribution. One wild card is housing. With homeownership rates stagnant for decades, the traditional engine of wealth-building may falter unless policy interventions—like down payment assistance or zoning reforms—make homebuying accessible again. Meanwhile, the rise of alternative assets (cryptocurrency, private equity, NFTs) could create new wealth divides, with early adopters reaping outsized returns while latecomers miss the boat. The question isn’t whether the average net worth will rise—it will—but whether the median will follow. That depends on whether America’s economic system rewards effort or just those who already have the most.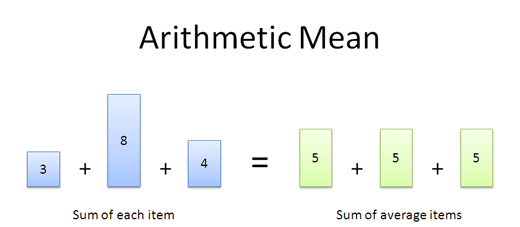
Conclusion
The numbers behind what is the average net worth of American citizen are more than cold statistics—they’re a mirror reflecting the nation’s priorities. When the average soars but the median stalls, it’s a sign that the system is working for some but not for most. The data doesn’t lie: wealth in America is inherited as much as it’s earned, and the barriers to entry are higher than ever. Yet these figures also hold promise. They expose problems, but they also illuminate solutions—from student debt forgiveness to universal childcare—that could level the playing field. For individuals, the takeaway is clear: net worth isn’t fixed. It’s shaped by decisions—where you live, how you save, whether you invest—and by circumstances beyond your control, like race, education, and luck. The average may be a moving target, but the median remains a stubborn benchmark of progress. Closing the gap won’t happen overnight, but understanding the numbers is the first step toward demanding change.Comprehensive FAQs
Q: Why does the average net worth differ so much from the median?
The average (mean) is skewed by ultra-high-net-worth individuals, while the median represents the middle point of all households. For example, if one household is worth $10 million in a group of 100, the average rises dramatically, but the median—where half are above and half below—remains closer to the typical household’s reality.
Q: How often is the Federal Reserve’s net worth data updated?
The Survey of Consumer Finances is conducted every three years, with the most recent data (as of 2024) covering 2022. The next update is expected in 2025, based on 2024–2025 surveys.
Q: Does student debt significantly impact net worth?
Yes. Households with student debt have a median net worth 40% lower than those without, according to the Federal Reserve. For young adults, student loans often delay homeownership or retirement savings, further suppressing net worth growth.
Q: How does homeownership affect net worth?
Homeowners have a median net worth 8x higher than renters ($255,000 vs. $36,100). Primary residences account for 60% of the typical American’s wealth, making housing the single largest driver of net worth disparities.
Q: Are there regional differences in net worth?
Yes. The District of Columbia leads with an average net worth of $1.2 million, while Mississippi trails at $160,000. Coastal states (California, New York) have higher averages due to stock ownership and high home values, while Rust Belt states lag due to industrial decline.
Q: How does marriage impact net worth?
Married couples have a median net worth 50% higher than single individuals ($168,600 vs. $111,700). This reflects combined income, shared assets, and tax benefits, though divorce can reverse these gains quickly.
Q: What’s the relationship between education and net worth?
Households headed by someone with a bachelor’s degree have a median net worth nearly 3x higher than those without a high school diploma ($168,600 vs. $60,300). Advanced degrees (master’s, PhD) correlate with even greater wealth accumulation.
Q: Can net worth be negative?
Yes. About 10% of U.S. households have negative net worth, primarily due to high debt (student loans, credit cards) with few assets. This group is disproportionately young, low-income, or minority.
