
The Complete Overview of the Average Net Worth of a 40-Year-Old Man
The average net worth of a 40-year-old man varies dramatically by country, economic system, and social policies. In the U.S., Federal Reserve data suggests figures around $400,000–$500,000 for the median household headed by a man in this age group, though the mean (average) skews higher due to outliers like executives or entrepreneurs. The UK’s Office for National Statistics places the median wealth of a 40-something male closer to £250,000–£300,000, with homeownership being the single largest asset for most. These numbers reflect decades of compounding—salary growth, retirement contributions, and (for some) real estate appreciation. Yet they also mask volatility: the 2008 financial crisis or the COVID-19 pandemic could have derailed early accumulators, while others benefited from low interest rates and bull markets. What these averages don’t capture is the net worth gap between genders, races, and education levels. A 40-year-old Black man in the U.S. has a median net worth of $24,100, per the Federal Reserve—less than 6% of the white male median. Similarly, a college degree correlates strongly with higher net worth at 40, not just because of higher earnings but because of access to financial advice and asset-building tools. The average net worth of a 40-year-old man is thus less a universal metric and more a reflection of systemic advantages—or their absence. Even within affluent groups, lifestyle choices play a role: the man who maxed out a 401(k) every year versus the one who treated his first home as an ATM.Historical Background and Evolution
The concept of tracking net worth by age emerged in the late 20th century as financial literacy became a mainstream topic. Before then, wealth was discussed in terms of generational legacies or land ownership, not liquid assets. The rise of defined-contribution retirement plans (like 401(k)s) in the 1980s shifted the burden of saving onto individuals, making net worth a personal metric rather than an employer-provided guarantee. This change coincided with the average net worth of a 40-year-old man becoming a proxy for economic health—especially as pensions declined and Social Security’s solvency came into question. The 2000s introduced another layer: the housing bubble and its aftermath. For those who bought homes in the mid-2000s, equity became a major component of their net worth at 40. Those who lost homes in foreclosures saw their wealth reset to near-zero. The Great Recession also exposed the fragility of stock-based wealth; men who had heavily invested in employer stock (e.g., Enron employees) saw their net worths collapse. Post-2010, the recovery favored those with diversified portfolios or cash reserves, widening the gap between those who could ride out downturns and those who couldn’t.Core Mechanisms: How It Works
Net worth at 40 isn’t the result of a single decision but a series of compounding effects. The most predictable factor is earnings trajectory: a man who entered the workforce in his early 20s and saw consistent salary growth will naturally outpace someone who faced stagnation or career setbacks. For example, a software engineer in Silicon Valley will accrue wealth faster than a retail worker in the same age bracket, even with similar savings rates. Tax policies also play a role—capital gains rates, mortgage interest deductions, and student loan forgiveness programs can tilt the scales for some while leaving others behind. Asset allocation is the second lever. A 40-year-old who prioritized homeownership may have built equity, but if that home is their sole major asset, they risk concentration. Those who diversified into stocks, bonds, or rental properties benefit from market returns. The average net worth of a 40-year-old man often assumes a balanced mix, but in reality, many are still in the accumulation phase, with retirement accounts and real estate as their primary stores of value. Debt management is the third critical factor: carrying high-interest debt (e.g., credit cards) can erode net worth, while leveraging low-interest debt (e.g., a mortgage) can accelerate asset growth.Key Benefits and Crucial Impact
Understanding the average net worth of a 40-year-old man isn’t just academic—it’s a mirror for economic mobility. For policymakers, these figures highlight disparities that require intervention, whether through education reform, wealth-building programs, or tax incentives. For individuals, they serve as a reality check: if your net worth is below the median, it may signal a need to adjust spending, increase income, or seek financial advice. The data also underscores the importance of early financial habits. A man who saved aggressively in his 20s and 30s will have a far different net worth at 40 than one who deferred saving until later. The psychological impact is equally significant. Hitting or exceeding the average net worth for your age group can provide a sense of security, while falling short may trigger anxiety. Financial therapists note that net worth comparisons often fuel guilt or envy, particularly among peers. Yet the most critical insight is that averages are just starting points—not destinations. A 40-year-old with a net worth below the median might still be on track if their expenses are low, their skills are in demand, and their health is good. Conversely, someone above the average could be living paycheck-to-paycheck if their lifestyle outpaces their income."Net worth is a snapshot, not a story. The real question isn’t whether you meet the average, but whether your path is sustainable given your goals." — Andrew Hallam, author of The Millionaire Fastlane
Major Advantages
- Leverage for future growth: A solid net worth at 40 provides options—early retirement, career pivots, or investments in education for children.
- Debt flexibility: Higher net worth often means better access to low-interest loans or the ability to refinance high-cost debt.
- Risk tolerance: Asset accumulation allows for more aggressive investing (e.g., startup equity, real estate) without derailing financial stability.
- Legacy planning: Wealth at this stage enables estate planning, charitable giving, or intergenerational transfers.

Comparative Analysis
| Factor | Impact on Net Worth at 40 |
|---|---|
| Education Level | College graduates earn ~$1M+ more over a lifetime; net worth gap at 40: ~$200K vs. high school grads. |
| Homeownership | Owners have ~40x the net worth of renters; equity builds wealth faster than rent payments. |
| Marital Status | Married men accumulate wealth ~30% faster due to dual incomes and shared expenses. |
| Investment Strategy | Index fund investors outpace active traders; time in market beats timing the market. |
| Geographic Location | Urban vs. rural divides: coastal cities inflate housing costs; rural areas offer lower cost of living. |
Future Trends and Innovations
The average net worth of a 40-year-old man will continue evolving with technological and economic shifts. Gig economy growth means more men will have irregular incomes, requiring adaptive saving strategies. Meanwhile, AI and automation may disrupt traditional career paths, forcing mid-career pivots. Those who can reskill or leverage digital assets (e.g., crypto, NFTs) could see their net worths diverge sharply from the average. On the policy front, wealth taxes or expanded child tax credits could either accelerate or slow accumulation depending on implementation. Demographic trends will also play a role. As millennials reach 40, their net worth at 40 may reflect higher student debt burdens but also greater financial literacy from open-access tools like robo-advisors. The rise of passive income streams (dividends, rental yields) could redefine what "average" looks like—shifting from homeownership-centric wealth to diversified portfolios. One certainty: the gap between those who plan and those who react will widen, making early financial education more critical than ever.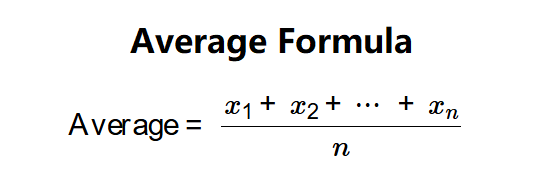
Conclusion
The average net worth of a 40-year-old man is a useful benchmark, but it’s only the beginning of the story. Behind every number lies a unique combination of choices, circumstances, and luck. The real measure of financial health isn’t whether you hit the median but whether your wealth aligns with your values and goals. For some, that means aggressive growth; for others, it’s stability and security. What matters most is recognizing that net worth isn’t static—it’s a living document shaped by every decision, from the first paycheck to the last retirement contribution. The conversation around wealth at 40 should focus less on comparisons and more on action. Whether you’re above, below, or near the average, the next decade offers opportunities to refine your strategy. The key is to move beyond the headline figures and ask: What does my net worth say about my future?Comprehensive FAQs
Q: How does the average net worth of a 40-year-old man compare to a woman’s?
The gap is significant. In the U.S., the median net worth for a 40-year-old woman is roughly 60% that of a man, per Federal Reserve data. Factors include wage disparities, career interruptions (e.g., childcare), and longer lifespans requiring more savings.
Q: Can a 40-year-old with no savings still build wealth?
Yes, but it requires aggressive action. Prioritizing high-earning skills, cutting expenses, and leveraging catch-up contributions (e.g., IRA limits) can accelerate growth. Side hustles or rental income can also bridge the gap.
Q: Does homeownership always boost net worth at 40?
Not necessarily. If the home is leveraged with high debt or in a declining market, equity gains may not offset costs. Renting in high-opportunity areas (e.g., near job hubs) can sometimes yield higher net worth growth.
Q: How does divorce affect a 40-year-old man’s net worth?
Divorce typically reduces net worth by 30–50% due to asset splits, legal fees, and alimony. Men often face larger hits if they were primary earners, though child support can offset some losses over time.
Q: Is the average net worth figure accurate for freelancers?
No. Freelancers’ net worths are more volatile due to irregular income. Many underreport assets or lack retirement accounts, skewing their net worth at 40 lower than traditional employees.
Q: Can inherited wealth skew the average?
Yes. Inheritances can double or triple net worth overnight, but they’re not reflected in median averages. Studies show 20% of U.S. wealth comes from inheritance, disproportionately benefiting higher-income groups.
Q: How does student loan debt impact net worth at 40?
Heavily. A 40-year-old with $50K in student loans may have $100K–$150K less in net worth than a peer with no debt, due to delayed homebuying or investing. Public Service Loan Forgiveness can help, but repayment terms vary widely.
Q: What’s the biggest mistake people make with net worth at 40?
Assuming they’ve done enough. Many underestimate future expenses (aging parents, healthcare) or overestimate Social Security benefits. Others fail to diversify, keeping all wealth tied to a single asset (e.g., a business or home).
