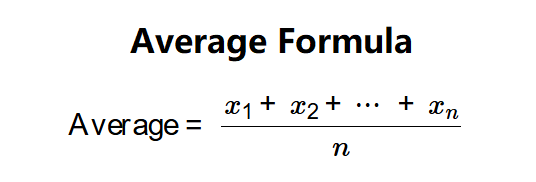
Common Myths About the Average Per Capita Net Worth in the US
The first myth is that the average per capita net worth in the US tells us how most Americans are faring financially. In reality, it’s a mean reversion trap: a handful of billionaires and high-net-worth households drag the average upward while the median—where half the population falls below—paints a far bleaker picture. The Fed’s data shows that the top 10% of households hold roughly 70% of all liquid assets, meaning the average per capita net worth in the US is often a phantom metric, detached from the lived experience of the 90% who don’t own private jets or unlisted tech stakes. Worse, the numbers don’t account for liquidity crises: a retiree with a paid-off home may have a high net worth on paper, but if their Social Security is their only income stream, that wealth is effectively illiquid. Another persistent misconception is that recent rises in the average per capita net worth in the US reflect broad-based economic improvement. The truth is that much of the post-2020 surge was driven by two factors: asset inflation (soaring home prices and stock markets) and debt forgiveness. Student loan cancellations, pandemic-era stimulus, and mortgage forbearance temporarily padded balance sheets, but these were one-time transfers, not sustainable wealth-building. The average per capita net worth in the US doesn’t distinguish between a family that inherited a vacation home and one that scraped together a down payment; it treats both as equal contributors to the national ledger. Economists like Edward N. Wolff have noted that real net worth growth—adjusted for inflation and debt—has stagnated for the bottom 90% since the 1980s, despite the headline numbers suggesting otherwise. A third myth frames the average per capita net worth in the US as a predictor of future economic mobility. The data suggests the opposite: wealth begets wealth, and the average obscures the intergenerational transmission of advantage. A 2022 Brookings Institution study found that children born into the top 20% of the wealth distribution are 10 times more likely to remain there than those in the bottom 20%. When policymakers or analysts cite the average per capita net worth in the US, they’re often describing a system where mobility is rare, and the starting line is already tilted. The numbers don’t capture the fact that a young professional in Detroit may have a net worth of $50,000, while their counterpart in San Francisco—with the same salary—could be sitting on $300,000 thanks to home equity alone. Geography, not income, dictates the average.Myth 1: The average per capita net worth in the US has risen steadily since the 2008 financial crisis
The narrative that the average per capita net worth in the US has rebounded uniformly since 2008 ignores the asset class divide. While stock portfolios and real estate values recovered quickly for those who owned them, wages and incomes for the bottom 60% did not. The average per capita net worth in the US surged in the years after the crisis, but that was largely because the rich got richer: the top 1% saw their net worth increase by $16.5 trillion between 2009 and 2021, according to the Fed. For the bottom 50%, the gains were negligible. The average doesn’t account for the fact that 40% of Americans have zero or negative net worth, meaning any rise in the mean is a statistical illusion, not a reflection of widespread prosperity. What’s more, the recovery wasn’t uniform across regions. States like Mississippi and West Virginia still have average per capita net worth figures below $100,000, while California and New York hover around $300,000 or higher. The average per capita net worth in the US masks these disparities, presenting a national picture that bears little resemblance to the financial reality of rural America or post-industrial cities. Even within states, ZIP code determines net worth more than income does. A teacher in a high-tax district may have a lower net worth than a barista in a low-cost area, simply because housing costs eat into savings. The average smooths over these fractures, offering a false sense of economic equilibrium.Myth 2: Rising home values mean most Americans are wealthier
The assumption that higher home prices translate to broader wealth is one of the most dangerous oversimplifications in financial reporting. Yes, home equity is the largest component of household net worth—accounting for nearly 40% of the total—but not everyone benefits equally. The average per capita net worth in the US climbs when housing markets inflate, but for renters, gig workers, and young adults priced out of ownership, that wealth is invisible. In 2022, 36% of Americans under 35 had no home equity at all, meaning the average per capita net worth in the US doesn’t reflect their financial reality. Even for homeowners, the gains are uneven: a family that bought a house in 2012 saw their equity double by 2020, while someone who bought in 2020 may still be underwater if prices correct. The Fed’s data also ignores leverage risk. Many homeowners treated their properties as ATMs during the pandemic, tapping into equity for renovations or debt consolidation. While this boosted reported net worth, it also increased financial vulnerability. If home prices dip—even slightly—the average per capita net worth in the US could drop sharply, yet the narrative of "wealthy homeowners" persists. Economists warn that overleveraged households are more likely to face foreclosure in a downturn, but this risk is absent from aggregate net worth statistics. The average tells us nothing about the stability of that wealth, only its nominal value at a single point in time.Myth 3: The average per capita net worth in the US reflects retirement security
The idea that net worth alone guarantees retirement security is a myth perpetuated by static snapshots. The average per capita net worth in the US includes assets like 401(k)s and IRAs, but it doesn’t account for sequence-of-returns risk, healthcare costs, or the fact that many retirees rely on home equity lines of credit. A 65-year-old with a $500,000 net worth may be secure if they own their home outright, but a 65-year-old with the same net worth but $200,000 in remaining mortgage debt faces a very different reality. The average per capita net worth in the US doesn’t distinguish between liquid wealth (cash, stocks) and illiquid wealth (a home that can’t be sold quickly), yet the latter is often the bulk of what’s reported. Worse, the numbers don’t reflect longevity risk. Someone with a high net worth at 65 might outlive their savings if they don’t account for 30 years of healthcare and inflation. The average per capita net worth in the US is a point-in-time metric, not a projection. Studies from the Urban Institute show that 40% of near-retirees have less than $50,000 in retirement savings, yet their net worth might appear robust if they own a home. The average obscures the fact that for many, retirement isn’t about wealth—it’s about asset liquidity and cash flow. A high net worth on paper means little if it can’t be converted into income.
What Holds Up to Scrutiny
At its core, the average per capita net worth in the US is a useful but limited tool. When properly contextualized, it reveals structural imbalances: the concentration of wealth in older cohorts, the racial wealth gap (where Black and Latino households have less than 20% of the net worth of white households), and the asset poverty of renters. The data isn’t wrong—it’s just incomplete. The Fed’s survey methodology is robust, but its limitations become clear when overlaid with other datasets, such as the Survey of Household Economics and Decisionmaking (SHED), which tracks spending and debt in real time. Together, they show that while the average per capita net worth in the US may tick upward, debt levels and liquidity constraints often offset those gains for the majority. What the average doesn’t tell us is how wealth is used. A family with a high net worth might be drowning in credit card debt, while another with a lower net worth could be debt-free and financially resilient. The average per capita net worth in the US is a stock measure, not a flow measure. It doesn’t capture the velocity of money—how quickly assets can be converted into income—or the opportunity cost of tying wealth up in illiquid assets like real estate. For policymakers, the real insight lies in wealth mobility studies, which show that the average is less important than the volatility of individual trajectories. A household’s net worth can swing wildly over a decade, but the average smooths those fluctuations into a single number."Net worth is a snapshot, not a movie." — Edward N. Wolff, Professor of Economics at NYU
| Common Belief | What the Evidence Says |
|---|---|
| The average per capita net worth in the US has doubled since 2000. | It has, but 80% of that growth is concentrated in the top 10%. The median has grown by less than 50%. |
| Homeownership is the surest path to wealth. | Only for those who buy at the right time. Renters in high-cost areas may accumulate more liquid assets over a lifetime. |
| The average per capita net worth in the US reflects retirement readiness. | It does not. Many retirees rely on reverse mortgages or part-time work; net worth alone doesn’t predict cash flow. |
| Young adults are catching up in net worth. | They’re not. The average per capita net worth for those under 35 is $76,000—but 40% have zero or negative net worth. |
Why the Confusion Persists
Part of the problem is media simplification. When the Fed releases its triennial report, journalists often pull the headline average per capita net worth figure without drilling into the underlying data. The result is soundbite economics: "Americans are wealthier than ever!"—without explaining that this wealth is unevenly distributed. Another issue is political framing. Conservatives may highlight rising averages to argue for tax cuts on capital gains, while progressives cite stagnant median wealth to push for wealth taxes. Both sides use the same data to make opposing points, creating a perception gap where the average per capita net worth in the US becomes a proxy for ideology rather than a neutral statistic. The third factor is cognitive bias. Humans are wired to focus on relative standing—how we compare to others—rather than absolute measures. When the average per capita net worth in the US rises, people assume they’re doing better, even if they’re not. This is the "keeping up with the Joneses" effect, where personal finance becomes a social comparison game. The average also suffers from survivorship bias: it includes only those who haven’t been wiped out by divorce, medical bankruptcy, or job loss. The net worth of a family that lost everything in 2008 isn’t part of the average anymore, even if their pre-crisis wealth was once above average. The numbers tell us more about who’s still standing than about the full spectrum of financial experiences.
Conclusion
The average per capita net worth in the US is neither a failure of data nor a conspiracy—it’s a necessary but imperfect measure. Its value lies in exposing disparities, not in providing comfort. The real story isn’t that Americans are wealthier (they’re not, collectively), but that wealth is concentrated in ways that defy mobility. The average tells us that the system rewards those who already have advantages, and it does little to help those left behind. For policymakers, the takeaway should be clear: wealth is not the same as income, and net worth doesn’t equal financial security. The conversation about the average per capita net worth in the US must shift from celebrating the numbers to asking who’s missing from them—and why. The next time you see a headline about the average per capita net worth in the US, ask: Who’s being counted? What’s being left out? The answer will tell you more about America’s economic divides than any single statistic ever could.Comprehensive FAQs
Q: How often is the average per capita net worth in the US updated?
The Federal Reserve’s Survey of Consumer Finances, which provides the most cited estimates, is conducted every three years. The most recent full dataset (2022) was released in 2023, with supplemental data on asset prices updated annually. However, these figures lag behind real-time economic shifts, such as stock market volatility or housing market corrections.
Q: Does the average per capita net worth in the US include debt?
Yes, but with a critical caveat. Net worth is calculated as total assets minus total liabilities (debt). However, the average per capita net worth in the US often overstates financial health because it treats secured debt (like mortgages) differently from unsecured debt (credit cards, student loans). A homeowner with a $500,000 house and a $400,000 mortgage may appear wealthy on paper, but their liquidity is far lower than someone with $500,000 in cash and no debt.
Q: Why is the average per capita net worth in the US higher than the median?
The average (mean) is skewed upward by outliers—a small number of ultra-high-net-worth individuals. For example, if 90% of Americans have $50,000 in net worth and 10% have $5 million, the average would be $545,000, while the median (the middle point) would be $50,000. The average per capita net worth in the US is typically 2-3 times higher than the median, highlighting extreme wealth concentration.
Q: Can the average per capita net worth in the US be used to compare countries?
With extreme caution. Cross-country comparisons are complicated by different data collection methods, currency fluctuations, and cultural attitudes toward debt and savings. For instance, the average per capita net worth in the US is inflated by high homeownership rates and stock market participation, while countries with stronger social safety nets (like Germany or Sweden) may have lower average net worths but higher quality of life due to universal healthcare and education. The OECD’s Household Wealth Statistics provide a more standardized (but still imperfect) framework for comparison.
Q: How does the average per capita net worth in the US vary by race?
Racial disparities are stark. According to the Fed’s data, white households have a median net worth of $188,200, while Black households have $24,100 and Latino households have $36,100. The average per capita net worth in the US obscures this gap because it includes a higher proportion of wealthy white households in the calculation. Historically, redlining, wealth taxes, and wage gaps have created a racial wealth divide that persists even when incomes converge. Closing this gap would require policies targeting homeownership access, inheritance equity, and student debt relief—none of which are reflected in net worth averages.
