
The Short Answers
- The average adult net worth in the U.S. is estimated around $120,000 (median), but this masks extreme inequality—top 10% hold 70% of wealth.
- Homeownership is the single biggest driver of net worth; renters’ figures are typically 10–20 times lower.
- Generational wealth gaps persist: Gen X’s net worth is double that of Millennials at the same age, largely due to housing market timing.
- Student debt suppresses net worth for younger adults, even when incomes are comparable to older generations.
- Regional disparities are stark—Washington, D.C., residents report net worth figures 3x higher than those in Mississippi, adjusted for cost of living.

Deep Dive: The Full Picture
The average adult net worth is a composite of assets minus liabilities, but the assets themselves are unevenly distributed. A 2023 Federal Reserve report showed that the median net worth for white households was nearly eight times that of Black households, a gap that persists even after controlling for income. This isn’t just about earnings—it’s about inherited wealth, historical redlining, and the compounding effect of homeownership. A home purchased in 1980 is worth far more today than one bought in 2020, even if the buyer’s salary adjusted for inflation remained the same. The data also reveals a paradox: while the average adult net worth has risen in nominal terms over the past 20 years, real growth has been minimal when adjusted for inflation and healthcare costs. The median American’s net worth in 2000 was roughly $60,000 (adjusted for today’s dollars); by 2022, it had grown to just over $100,000. That’s progress, but it’s progress that’s been concentrated in the top 20%. For the bottom 40%, net worth has stagnated—or declined—due to rising costs and stagnant wages.The Context You Need
Understanding the average adult net worth requires recognizing that wealth isn’t just about money in the bank. It’s about access: to education that leads to high-paying jobs, to neighborhoods where home values appreciate, and to family networks that provide financial safety nets. A 2021 Pew Research study found that 62% of wealth for the top 1% comes from inherited assets or capital gains, not salaries. Meanwhile, the bottom 50% derive nearly all their wealth from labor income. This structural divide explains why the average adult net worth looks so different across demographics. The housing market is the great equalizer—or the great divider. Homeownership accounts for roughly 70% of the net worth of older Americans, but only 30% for those under 35. The reason? Younger buyers face higher down payments, student debt, and stagnant wage growth. Even when they do buy, they’re entering a market where prices have outpaced income growth for over a decade. The result? A average adult net worth that’s artificially inflated by the few who’ve benefited from past market booms, while the many struggle to catch up.The Mechanics
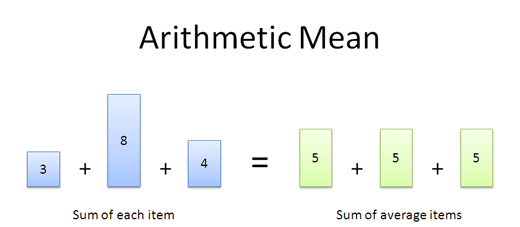
The average adult net worth is calculated by subtracting liabilities (debt, mortgages, loans) from assets (cash, investments, real estate, retirement accounts). But the math hides critical nuances. For example, a retiree with a paid-off home and a 401(k) may have a net worth of $500,000, while a 30-year-old with the same income but student loans and a rental apartment might report just $20,000. Both are "average" in different contexts. The Federal Reserve’s Survey of Consumer Finances shows that average adult net worth spikes sharply after age 50, not because people earn more, but because debt burdens lighten and assets compound. Tax policy further distorts the picture. Capital gains taxes favor long-term investors, while payroll taxes hit wage earners harder. A homeowner selling a property after 10 years may owe little in taxes on the gain, while a renter saving the same amount in a brokerage account faces higher capital gains rates. This creates a feedback loop: those who inherit wealth or benefit from housing appreciation pay less in taxes relative to their income, widening the average adult net worth gap over time.Details That Change the Picture
The average adult net worth varies wildly by state. In Massachusetts, the median net worth is estimated at $180,000, thanks to high home values and a concentration of professional jobs. In West Virginia, it’s closer to $60,000. These differences aren’t just about income—they’re about opportunity. States with strong labor unions, progressive tax policies, and public education systems tend to have higher net worth figures, not because residents are inherently wealthier, but because systemic supports reduce volatility. Age is the most predictable factor. A 25-year-old’s net worth is typically $10,000–$30,000, while a 65-year-old’s is $200,000–$500,000. The jump isn’t linear—it’s exponential after 40, when home equity and retirement accounts kick in. This explains why Millennials, despite earning less than Gen X at the same age, are on track to have lower average adult net worth in retirement unless trends reverse."Wealth isn’t just about how much you earn; it’s about how much you keep—and how long you’ve had the chance to grow it." — Edward N. Wolff, Professor of Economics at NYU, author of The Asset Price Meltdown
| Demographic | Median Net Worth (Est.) |
|---|---|
| White households | $188,200 |
| Black households | $24,100 |
| Asian households | $96,400 |
| Hispanic households | $36,100 |
| Homeowners (all races) | $319,200 |
Conclusion
The average adult net worth is less a measure of individual success and more a reflection of structural advantages. It’s the product of policies that favor homeownership, tax breaks that benefit the wealthy, and a labor market that rewards experience over youth. The data isn’t wrong—it’s incomplete. Ignoring the context behind the numbers obscures the reality: for most people, building wealth is a marathon, not a sprint, and the starting line is often uneven. The conversation around net worth should shift from "how much do you have?" to "how did you get there?" Because the average adult net worth isn’t just a personal metric—it’s a barometer of economic fairness. And right now, the needle isn’t just stuck; it’s pointing in the wrong direction for too many.Comprehensive FAQs
Q: Why does the average adult net worth differ so much by race?
The gap stems from historical discrimination, including redlining, which denied Black and Hispanic families access to mortgages and wealth-building opportunities like homeownership. Today, lower homeownership rates and wage disparities contribute to the divide. Studies show that white families receive $150,000 more in wealth transfers (inheritance, gifts) than Black families over a lifetime.
Q: Does student debt really suppress net worth?
Yes. The Federal Reserve estimates that student loan debt reduces the net worth of borrowers by 15–20% compared to non-borrowers with similar incomes. Even after repayment, the opportunity cost—delayed home purchases, lower retirement savings—lingers for years.
Q: How does inflation affect the average adult net worth?
Inflation erodes purchasing power, but its impact on net worth depends on asset types. Cash and low-yield savings lose value, while real estate and stocks often outpace inflation over time. The average adult net worth in 1990 dollars would appear far lower today, even if nominal figures rose.
Q: Can you build wealth without homeownership?
It’s possible but harder. Renters rely on investments, high savings rates, or side income. Data shows renters’ net worth is typically 10–20 times lower than homeowners’, though urban professionals in high-cost cities may accumulate wealth through stocks or entrepreneurship.
Q: Why do older generations have higher net worth?
Compounding works over time. A 65-year-old’s assets—home equity, retirement accounts, decades of savings—benefit from market growth and lower debt burdens. Younger generations face higher costs (housing, healthcare) and student debt, delaying wealth accumulation.
Q: Does the average adult net worth include retirement accounts?
Yes, but definitions vary. The Federal Reserve’s data includes 401(k)s and IRAs, while some surveys exclude them. This can skew comparisons—retirement accounts are a major asset for older adults but may not reflect liquid wealth for younger workers.
Q: How does divorce impact net worth?
Divorce often splits assets but not liabilities equally. Studies show women’s net worth drops by 45% post-divorce, while men’s falls by 25%. Alimony and child support can offset this, but the long-term effect is a sharp decline in the average adult net worth for separated individuals.
Q: Are there ways to increase net worth without high income?
Yes: aggressive savings (e.g., maxing out retirement accounts), reducing high-interest debt, and investing in appreciating assets like real estate or index funds. Side hustles and skill-building (e.g., certifications) can also boost earning potential over time.
