
5 Things Worth Knowing About a Statement of Net Worth
The most valuable wealth disclosures aren’t just numbers—they’re the questions they answer. Here’s what separates a useful net worth summary from a meaningless ledger.1. It’s Not Just About the Number
A statement of net worth isn’t a vanity project. Its power lies in the process—the act of cataloging every asset, from a 401(k) to a vintage wine collection, and every liability, from student loans to a timeshare. The real value emerges when you cross-reference these entries with your goals. For example, a tech founder might list a startup’s equity as an asset, but without noting vesting schedules or dilution risks, that figure becomes misleading. A retiree might overlook the tax implications of converting a traditional IRA into a Roth. The net worth statement becomes a mirror: it reflects not just what you have, but what you don’t understand.2. Legal and Tax Implications Are Built In
Courts, creditors, and tax authorities demand financial asset disclosures for a reason. A divorce proceeding hinges on an accurate statement of net worth—one party’s omission of a hidden brokerage account can derail settlements. In bankruptcy, an inflated valuation of a primary residence might trigger fraud allegations. Even without legal pressure, the IRS scrutinizes high-net-worth individuals. A wealth summary that fails to account for offshore accounts or undeclared rental income invites audits. The key? Precision. A handwritten note in the margin—"This car is worth $25K (per Kelly Blue Book)"—can save years of disputes.3. Digital Assets Require Special Handling
Cryptocurrency, domain names, and even frequent-flier miles complicate traditional net worth calculations. A Bitcoin held in a cold wallet might be worth $50,000 today but $30,000 tomorrow. A domain like Insurance.com could be an illiquid asset worth six figures—or worthless if the market shifts. Financial advisors now recommend a separate digital asset ledger alongside the core statement of net worth. Tools like CoinTracker or Keeper automate this, but manual entries are still critical. Forgetting to update a crypto portfolio valuation could mean missing a tax deadline—or worse, losing access to funds if passwords aren’t documented.4. It’s a Living Document, Not a One-Time Task
A net worth statement frozen in 2020 is a relic. Markets fluctuate, debts are paid, inheritances arrive. Even a modest portfolio can swing by 20% in a year. The most effective wealth trackers treat their financial summaries as dynamic tools—revisited quarterly, if not monthly. Consider the case of a physician who, in 2018, listed her net worth at $1.2 million. By 2020, after selling a rental property and facing medical malpractice claims, her liquid net worth had dropped to $850,000. Without updating her asset disclosure, she nearly overleveraged for a new home—until her accountant flagged the discrepancy.5. The Right Format Matters More Than You Think
A statement of net worth isn’t a creative project. It’s a structured tool. The best formats separate assets into categories: - Liquid assets (cash, stocks, bonds) - Illiquid assets (real estate, collectibles) - Liabilities (mortgages, credit cards, loans) - Contingent liabilities (guarantees, legal judgments) A poorly organized wealth summary can obscure risks. For instance, listing a $500,000 home under "assets" without noting a $300,000 mortgage distorts true equity. Pro tip: Use a T-account style—debits on one side, credits on the other—to visualize net worth instantly.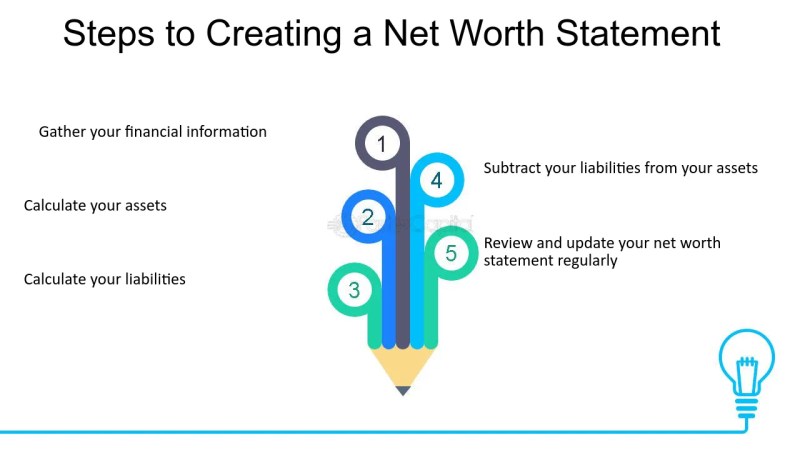
How These Facts Connect
A statement of net worth isn’t just a snapshot—it’s a system. The first three points (legal implications, digital assets, precision) highlight why accuracy matters. The last two (living document, format) ensure that accuracy is sustainable. Together, they reveal a truth: wealth management isn’t about hiding numbers; it’s about mastering them. The disconnect often lies in psychology. People treat their financial asset inventory like a chore—something to do "someday." But the moment you need it (a loan application, an inheritance dispute), the lack of a current net worth statement becomes a liability. The solution? Treat it as a financial health checkup: regular, thorough, and tied to actionable insights.| Key Insight | Why It Matters | Common Mistake | Fix |
|---|---|---|---|
| Not just a number | Reveals blind spots in asset/liability management. | Ignoring vesting schedules or off-balance-sheet liabilities. | Consult a CPA to classify assets by liquidity and risk. |
| Legal/tax implications | Protects against disputes and audits. | Underreporting rental income or overvaluing assets. | Use appraisals for high-value items; keep receipts for everything. |
| Digital assets | Prevents loss of access or tax misreporting. | Forgetting to log crypto wallets or domain registrations. | Use a password manager + dedicated ledger for digital holdings. |
| Living document | Ensures decisions are based on current data. | Updating only annually or never at all. | Set calendar reminders; automate updates where possible. |

Conclusion
A statement of net worth isn’t about bragging or stressing. It’s about clarity. The moment you stop treating it as a static document—and start using it to guide decisions—it transforms from a ledger into a strategic asset. Whether you’re planning an exit from your business, preparing for a divorce, or simply tracking progress toward financial independence, the wealth disclosure is your North Star. The hardest part isn’t the math. It’s the discipline. But here’s the irony: the people who avoid net worth statements often end up in worse financial shape. They miss opportunities, overpay taxes, or scramble during crises because they lack a baseline. The alternative? Own your numbers. Update them. Use them.Comprehensive FAQs
Q: Do I need a professional to prepare my statement of net worth?
A: Not necessarily, but a CPA or financial advisor can help with complex assets (e.g., trusts, private equity) or tax implications. For most individuals, a spreadsheet with clear categories suffices—just ensure you’re consistent in valuations.
Q: How often should I update my net worth statement?
A: At minimum, annually. High-net-worth individuals or those with volatile assets (crypto, startups) should update quarterly. The goal is to reflect current market values and life changes (marriage, inheritance, new debts).
Q: Can I use a free template from the internet?
A: Yes, but be cautious. Generic templates may lack fields for digital assets or contingent liabilities. Customize it to your needs—add columns for "fair market value" vs. "book value" if you’re tracking investments.
Q: What if my net worth drops significantly? Should I panic?
A: Not necessarily. A net worth decline can stem from debt repayment, market corrections, or strategic reinvestment. Compare it to your liquid net worth (cash + easily sellable assets) and long-term goals. Panic only if the drop is due to mismanagement or unforeseen liabilities.
Q: How do I handle assets with fluctuating values (e.g., art, stocks)?
A: Use the most recent appraised value for tangible assets (art, collectibles) and end-of-period balances for stocks/crypto. For illiquid assets, note a range (e.g., "Antique car: $40K–$50K per recent appraisals"). Avoid guessing—consult experts when in doubt.
Q: Is a net worth statement the same as a balance sheet?
A: Functionally, yes—but context matters. A personal net worth statement focuses on individual finances, while a corporate balance sheet includes revenue, expenses, and equity. Both follow the same assets = liabilities + equity formula, just for different purposes.
Q: What’s the best way to store my statement of net worth securely?
A: Use encrypted digital storage (e.g., LastPass Vault, Dropbox with password protection) and a physical copy in a safe deposit box. Never store it solely on your computer or in an unsecured cloud folder. Update access permissions if your situation changes (e.g., divorce, estate planning).
Q: Can I use my net worth statement for loan applications?
A: Yes, but lenders may require additional documentation (pay stubs, tax returns, asset appraisals). A personal net worth summary serves as a quick reference, but banks prefer verified figures. Always double-check their specific requirements.
