Common Myths About the Average Net Worth of Top 1 Percent in US
The first misconception is that the average net worth of top 1 percent in US is a fixed benchmark. In truth, it’s a moving target. The Fed’s estimates show that between 2016 and 2019, the top 1%’s share of national wealth grew from 32% to 38%. But this growth wasn’t uniform—it was driven by asset appreciation in coastal cities and tech hubs, while rural and midwestern households saw stagnation. The pandemic exacerbated this: while billionaires’ net worth surged by $2.1 trillion in 2020 (per Oxfam), the median wealth of the bottom 50% declined. The myth persists because media often cites single-year snapshots without context. Another false assumption is that the top 1% are uniformly "old money." The reality is that the average net worth of top 1 percent in US now includes a significant portion of self-made fortunes, particularly in tech, finance, and entertainment. A 2022 study by the Urban Institute found that 40% of millionaires under 40 had built their wealth through entrepreneurship or high-income professions, not inheritance. Yet cultural narratives still cling to the image of trust-fund heirs, ignoring how modern wealth creation—through startups, venture capital, or even social media—has democratized (to some extent) access to elite financial tiers.Myth 1: The top 1% all have "obscene" wealth
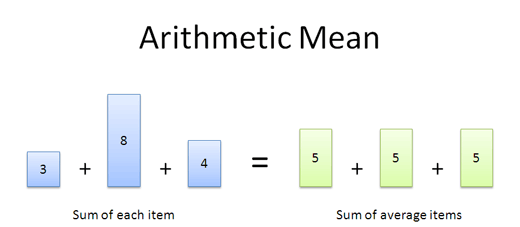
The term "obscene" implies uniformity, but the average net worth of top 1 percent in US masks a wide spectrum. The bottom rung of this group—households with net worths between $2 million and $5 million—often includes professionals like doctors, lawyers, or executives who’ve saved aggressively but lack the ultra-high-net-worth liquidity of the top 0.1%. Their wealth is tied to pensions, real estate, and 401(k)s, not unencumbered cash. Meanwhile, the top 0.1% (net worth >$30 million) hold 70% of the wealth of the entire 1%, according to the Federal Reserve. The distortion comes from how averages work. If you take the net worth of a $5 million physician and a $100 million hedge fund manager, the average is $52.5 million—but that’s not where most of the 1% reside. The median net worth (the middle point) is far more representative: around $3 million to $5 million for the bulk of this demographic. This is why economists prefer median measures when discussing wealth inequality, yet headlines often default to averages, which are skewed by outliers.Myth 2: Wealth in the top 1% is evenly distributed
The average net worth of top 1 percent in US suggests a broad distribution, but the data tells a different story. A 2023 analysis by the Institute for Policy Studies revealed that the wealthiest 0.0001%—just 1,300 households—hold more wealth than the entire bottom 90% combined. These families often control private jets, yachts, and art collections valued in the hundreds of millions, while the rest of the 1% may struggle with market volatility or illiquid assets. The concentration is extreme: the top 10% of the 1% own as much as the bottom 90%. This isn’t just about dollar figures—it’s about asset types. The ultra-wealthy rely on private equity, hedge funds, and real estate holdings that appreciate independently of broader market trends. The lower tiers of the 1% are more exposed to stock market fluctuations and may lack the diversified portfolios that insulate the elite. For example, a $5 million portfolio might be 60% in stocks, while a $50 million portfolio could be 30% in private assets with lower volatility. The perception of even distribution ignores these structural differences.Myth 3: The top 1%’s wealth is mostly liquid
One of the most persistent myths is that the average net worth of top 1 percent in US translates to easily accessible cash. In reality, much of this wealth is tied up in illiquid assets. A 2022 report by the Brookings Institution found that 60% of the top 1%’s wealth is held in real estate, private businesses, and illiquid investments—assets that can’t be quickly converted to cash without penalties. Even for those with high net worth, liquidity crises can arise, such as during the 2008 financial crisis, when many saw paper wealth evaporate overnight. The distinction matters because liquidity determines lifestyle flexibility. A family with $10 million in a single property may face foreclosure risks if markets shift, while another with diversified holdings can weather downturns. The Fed’s net worth figures don’t distinguish between these scenarios, leading to the false assumption that wealth equals spending power. This is why some in the top 1%—despite appearing affluent—may still live paycheck-to-paycheck if their assets are illiquid.
What Holds Up to Scrutiny
The most reliable data on the average net worth of top 1 percent in US comes from three sources: the Federal Reserve’s Survey of Consumer Finances, IRS tax filings, and studies by nonpartisan think tanks like the Urban Institute and Pew Research. These sources agree on key points: the top 1%’s share of wealth has grown since the 1980s, the median net worth is far lower than the average, and geographic disparities are stark. For example, the average net worth in San Francisco’s top 1% exceeds $20 million, while in rural Mississippi, it may not reach $1 million. What these sources also confirm is that wealth in the top 1% is not primarily held in cash or easily spendable forms. The majority is tied to assets that appreciate over time—stocks, real estate, and business equity—but these come with risks. The Fed’s data shows that the top 1%’s wealth grew by 27% between 2016 and 2019, but this growth was concentrated in the top 0.1%. The rest saw modest gains, often tied to home equity rather than speculative investments."The top 1% are not a monolith. Their wealth structures differ as much as their lifestyles do. The average net worth figure obscures the fact that most of this group are not billionaires—they’re high-net-worth individuals managing complex asset portfolios with varying degrees of liquidity." — Edward N. Wolff, Professor of Economics at NYU
| Common Belief | What the Evidence Says |
|---|---|
| The top 1% all have $10M+ in liquid assets. | Only the top 0.1% do; the rest have 60%+ in illiquid assets. |
| Wealth in the top 1% is evenly distributed. | The top 10% of the 1% hold as much as the bottom 90%. |
| The average net worth of top 1% is stable over time. | It fluctuates with market cycles (e.g., +27% 2016–2019, but volatile in recessions). |
| Most top 1% wealth comes from inheritance. | 40% of millionaires under 40 are self-made (Urban Institute). |
Why the Confusion Persists
The gap between perception and reality stems from how wealth data is presented. Media outlets often cite the average net worth of top 1 percent in US without clarifying that it’s an average—not a median—and thus skewed by outliers. Politicians and activists use these figures to argue for or against wealth taxes, but the data rarely supports their claims without nuance. For instance, a 2021 proposal to tax the top 1% at 60% would affect only the top 0.1%, not the broader group. Another factor is the lack of transparency in ultra-high-net-worth portfolios. The wealthiest individuals often hold assets in trusts, private companies, or offshore accounts that evade standard surveys. The IRS’s "Forbes 400" list, for example, excludes many ultra-wealthy individuals whose fortunes are tied to closely held businesses. This creates a blind spot in public data, reinforcing the myth that the top 1% is more homogeneous than it is.
Conclusion
The average net worth of top 1 percent in US is a useful but deceptive shorthand. It tells us that the wealthiest Americans are far richer than the median household—but it doesn’t explain how that wealth is structured, who truly benefits, or what risks they face. The data reveals a tiered system where the top 0.1% dominate, while the rest of the 1% navigate a landscape of debt, illiquid assets, and market exposure. Understanding this requires moving beyond averages to medians, asset classes, and geographic context. The conversation about wealth inequality often hinges on these numbers, but the reality is more complex. Policymakers, journalists, and the public must grapple with whether to focus on reducing the top 1%’s share of wealth or addressing the broader inequality between the 1% and the 99%. The average net worth of top 1 percent in US is just the starting point—not the answer.Comprehensive FAQs
Q: How is the top 1% defined in wealth studies?
The Federal Reserve defines the top 1% by net worth percentile, while the IRS uses income thresholds (currently >$539,000 annually). Wealth studies often blend both methods, but the Fed’s net worth data is more precise for asset-based analysis.
Q: Does the average net worth of top 1% include debt?
Yes. The Fed’s Survey of Consumer Finances subtracts liabilities (mortgages, student loans, business debt) from assets to calculate net worth. However, high-net-worth individuals often use leverage—e.g., mortgages on multiple properties—to inflate reported wealth temporarily.
Q: Are there regional differences in top 1% wealth?
Significant. In coastal cities (NYC, SF, LA), the average net worth of the top 1% exceeds $20 million, while in Rust Belt states, it may not reach $5 million. This reflects both income levels and asset appreciation rates.
Q: How does the top 1%’s wealth compare to the bottom 50%?
The bottom 50% hold about 2.6% of national wealth, while the top 1% holds ~38%. The median net worth for the bottom 50% is negative (due to debt), whereas the median for the top 1% is ~$3 million.
Q: Can someone in the top 1% lose their status quickly?
Yes. Market downturns, divorce, or poor investment choices can erode wealth. For example, during the 2008 crisis, some top 1% households saw net worths drop by 30–40%, though most recovered over time.
Q: What’s the biggest misconception about top 1% wealth?
That it’s uniformly "old money" or inherited. Studies show that 40% of millionaires under 40 are self-made, often through entrepreneurship, high-income careers, or asset accumulation (e.g., real estate, stocks).
Q: How accurate are public estimates of top 1% wealth?
Moderately accurate for broad trends but flawed in specifics. The Fed’s data is robust for the top 1%, but ultra-high-net-worth individuals (e.g., billionaires) are undercounted due to private holdings and offshore assets.
