
Common Myths About the Average Net Worth of American Households
The average net worth of American households is frequently cited as proof of economic health, but the narrative around it is riddled with oversimplifications. One persistent myth is that rising home values automatically translate to rising wealth for all homeowners. In reality, home equity gains disproportionately benefit older households, while younger buyers face higher prices and mortgage rates that erode disposable income. Another assumption is that stock market performance directly lifts the average net worth of American households. While true for those who own stocks—about 55% of households—it ignores the 45% who lack any exposure to equities. For them, the S&P 500’s gains mean little. The idea that the average net worth of American households has recovered from the 2008 financial crisis is also misleading. While the top 10% saw their wealth grow significantly, the bottom 90% remained stagnant for years. The post-pandemic rebound, driven by asset price inflation rather than wage growth, further widened the gap. Even the Federal Reserve’s own data shows that the median net worth of American households hasn’t kept up with inflation-adjusted income growth. These myths persist because they align with a narrative of broad-based prosperity—one that policymakers and financial institutions have an interest in promoting.Myth 1: The average net worth of American households reflects the financial health of the middle class.
The average net worth of American households is often used as a proxy for middle-class stability, but this ignores the fact that the middle class is a shrinking segment of the population. The median net worth—a better indicator of typical household wealth—paints a far bleaker picture. In 2022, the median net worth for the middle 60% of households was just $120,000, according to the Fed’s Survey of Consumer Finances. For the bottom 50%, it was $26,000. These figures suggest that the average net worth of American households is being pulled upward by a small elite, while the majority struggles with debt, stagnant wages, and limited asset accumulation. The middle class isn’t disappearing because people are getting richer; it’s disappearing because the cost of living—housing, healthcare, education—has outpaced wage growth for decades. The confusion stems from how wealth is distributed. The top 1% of households holds about 35% of all wealth, while the bottom 50% holds just 2.6%. This means that even modest increases in the wealth of the ultra-rich can skew the average net worth of American households upward without improving the financial security of the majority. For example, if 100 households have a net worth of $1 million each, and 900 have $10,000, the average is $109,000—but the typical household is far poorer. Policymakers and media outlets often focus on the average because it makes economic growth seem more widespread than it is, obscuring the reality that wealth accumulation is increasingly a privilege.Myth 2: Younger generations are catching up to previous ones in terms of the average net worth of American households.
Millennials and Gen Z are often portrayed as the "lost generation" when it comes to wealth, but the data suggests their financial struggles are less about laziness and more about structural barriers. The median net worth of American households headed by someone under 35 is $62,000, compared to $255,000 for those headed by someone 65 and older. This gap isn’t just about age—it’s about access. Younger households are more likely to rent, lack inheritance wealth, and face higher student debt burdens. The average net worth of American households for Gen X (now in their 40s and 50s) was also low at similar ages, but they benefited from a stronger housing market in the 1990s and 2000s. Today’s young adults entered the workforce during the Great Recession and its aftermath, compounding their challenges. The narrative that younger generations are failing to build wealth ignores the fact that the average net worth of American households has always been lowest for the youngest cohorts. What’s different now is the scale of the gap. In 1989, the median net worth of households headed by someone under 35 was about 15% of those headed by someone 65 and older. By 2022, that ratio had dropped to just 24%. This isn’t a failure of personal finance—it’s a failure of economic opportunity. Without policies that address student debt, housing affordability, and wage stagnation, the average net worth of American households will continue to reflect a system that rewards those who already have wealth.Myth 3: The average net worth of American households is rising because the economy is strong.
Asset price inflation—particularly in housing and stocks—has artificially boosted the average net worth of American households in recent years, but this wealth is largely illusory for those who don’t own those assets. The S&P 500’s surge since 2020 added trillions to household balance sheets, but only if you’re one of the 55% who own stocks. For the rest, the gains mean little. Similarly, home values have risen sharply, but many potential buyers are priced out of the market entirely. The average net worth of American households doesn’t account for the fact that younger generations are delaying homeownership or living with family to save money. Economic strength isn’t just about asset prices—it’s about whether those gains trickle down to wages, savings, and debt relief. The Fed’s data shows that the median net worth of American households grew by about 37% between 2019 and 2022, but this was driven almost entirely by the top 10%. The bottom 50% saw no real growth in median net worth over the same period. When economists talk about a "strong economy," they often mean corporate profits and stock market returns—not the financial security of average households. The average net worth of American households may be higher on paper, but for millions, it’s a statistic that bears little relation to their day-to-day financial reality.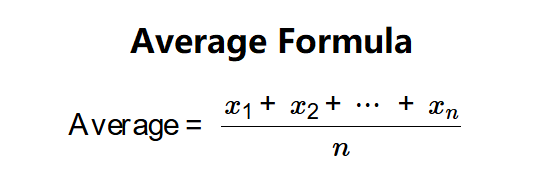
What Holds Up to Scrutiny
When stripped of myths, the average net worth of American households reveals three verifiable truths. First, wealth in the U.S. is highly unequal. The top 10% of households hold 70% of all wealth, while the bottom 50% hold just 2.6%. Second, the average net worth of American households is heavily influenced by age and homeownership. Older households and homeowners dominate the wealth distribution, while younger renters and non-homeowners lag far behind. Third, racial and ethnic disparities are stark. The median white household has nearly ten times the wealth of the median Black household, and eight times that of the median Hispanic household. These patterns aren’t new, but they’ve deepened over time. The Federal Reserve’s Survey of Consumer Finances is the most reliable source for tracking the average net worth of American households, but even its data has limitations. It’s conducted every three years, meaning it lags behind real-time economic shifts. It also relies on self-reported data, which can understate wealth (especially among the poor) or overstate it (among the wealthy). Despite these caveats, the survey provides the clearest picture of trends. For example, it shows that the average net worth of American households peaked in 2007 at $126,400 (inflation-adjusted), fell to $69,200 in 2010 post-crisis, and then climbed to $138,000 by 2022. But the median—$120,000 in 2022—tells a different story: most households are not wealthy by any standard."Wealth inequality is not just about income—it’s about access to assets that appreciate over time. Homeownership, stock ownership, and inheritance are the three biggest drivers of wealth accumulation. If you don’t have any of those, you’re starting from a massive disadvantage." —Edward N. Wolff, Professor of Economics at NYU and author of House of Debt
| Common Belief | What the Evidence Says |
|---|---|
| The average net worth of American households has fully recovered from the 2008 crisis. | Only the top 10% have seen meaningful recovery; the bottom 50% remain near pre-crisis levels. |
| Younger generations are saving less than previous ones. | They’re saving at similar rates, but face higher costs for housing, education, and healthcare. |
| The average net worth of American households is evenly distributed across races. | White households hold 10x the median wealth of Black households and 8x that of Hispanic households. |
| Stock market gains benefit most households. | Only about 55% of households own stocks; the rest see no direct benefit from market growth. |
Why the Confusion Persists
The average net worth of American households is a moving target, and the data used to track it is often misinterpreted. Part of the problem lies in how wealth is measured. Net worth includes assets like homes, stocks, and retirement accounts, but it also accounts for liabilities like mortgages and student loans. For young households with high debt but few assets, net worth can appear artificially low—even if their financial situation is stable. Meanwhile, older households with paid-off mortgages and accumulated assets show higher net worth, creating a misleading age-based trend. Another source of confusion is the role of policy. Tax cuts, student loan forgiveness, and housing subsidies can temporarily alter the average net worth of American households, but their long-term effects are debated. For example, the 2017 Tax Cuts and Jobs Act benefited high-income households far more than middle- or low-income ones, widening inequality. Yet discussions about wealth often focus on broad economic indicators like GDP growth rather than how those gains are distributed. The media also plays a role by highlighting stock market records or home price surges without explaining who actually benefits. Without this context, the average net worth of American households becomes a static number rather than a reflection of systemic economic forces.
Conclusion
The average net worth of American households is less a measure of collective prosperity and more a symptom of an economy that rewards asset ownership over wage growth. The data shows that wealth accumulation is not just about personal discipline—it’s about access to opportunities that most people lack. Homeownership, stock ownership, and inheritance are the three pillars of wealth, and without them, the average net worth of American households remains out of reach for millions. The gap between the average and the median underscores how skewed the distribution is, while racial and generational disparities reveal deeper structural issues. Moving forward, discussions about the average net worth of American households must move beyond surface-level statistics to address the policies that shape wealth inequality. Expanding access to homeownership, promoting retirement savings for low-wage workers, and reforming student debt could help narrow the gap. But without targeted interventions, the average net worth of American households will continue to reflect an economy that works for those at the top—and leaves the rest behind.Comprehensive FAQs
Q: How is the average net worth of American households calculated?
The Federal Reserve’s Survey of Consumer Finances estimates household net worth by subtracting liabilities (debt) from assets (home equity, retirement accounts, stocks, etc.). The average is derived by summing all net worth values and dividing by the number of households. The median, however, splits the population in half—providing a better sense of what a "typical" household holds.
Q: Why does the average net worth of American households differ so much from the median?
The average (mean) is skewed by ultra-high-net-worth individuals, while the median represents the middle point of the distribution. For example, if 90% of households have $50,000 in net worth and 10% have $5 million, the average would be far higher than the median. This is why economists often prefer the median when discussing household wealth.
Q: Does the average net worth of American households include debt?
Yes. Net worth is calculated as total assets minus total liabilities (mortgages, student loans, credit card debt, etc.). A household with a high mortgage balance but little savings may have a negative net worth, even if their monthly income is sufficient.
Q: How does age affect the average net worth of American households?
Older households accumulate more wealth over time due to home equity, retirement savings, and longer investment horizons. The median net worth for households headed by someone 65+ is nearly ten times that of those headed by someone under 35. This gap reflects decades of wage growth, asset appreciation, and inheritance.
Q: Are racial disparities in the average net worth of American households improving?
No. While wealth gaps have narrowed slightly in recent years, they remain stark. The median white household holds nearly ten times the wealth of the median Black household and eight times that of the median Hispanic household. Policies like redlining, predatory lending, and wage discrimination have historically contributed to this divide.
Q: How does the average net worth of American households compare to other developed nations?
The U.S. has higher wealth inequality than most developed nations, but its average net worth is also higher due to asset price inflation. For example, Canada’s median net worth is lower than the U.S., but its distribution is less skewed. Countries with stronger social safety nets—like Germany or Sweden—see less wealth concentration at the top.
Q: Can the average net worth of American households be used to predict economic stability?
Not reliably. While rising net worth can indicate asset price growth, it doesn’t reflect wage growth, job security, or debt burdens. A household with high net worth but high debt may still struggle financially. Economists prefer looking at median income, unemployment rates, and consumer debt levels for a clearer picture of stability.
