
Where It All Began
The financial foundation of today’s 20 year olds was laid in the aftermath of the 2008 crash. When the Great Recession hit, young adults entering the workforce faced stagnant wages, shrinking job markets, and parents who could no longer bail them out as easily. The average net worth of 20 year olds in the early 2010s reflected this: negative or near-zero for many, as student debt ballooned and entry-level wages failed to keep pace with rising costs. The message was clear—financial independence at 20 was no longer the default. Before that, the late 1990s and early 2000s had offered a different picture. The dot-com boom and housing bubble had left some young adults with early exposure to market gains, even if the crash that followed wiped out those gains for others. For those who inherited wealth or came from families with financial literacy, the average net worth of 20 year olds could still be respectable—perhaps $10,000 to $20,000, depending on location and upbringing. But for the majority, especially those without a safety net, the numbers were far bleaker. The gap between haves and have-nots was widening, and the deck was stacked against those just starting out.The Early Signs
By the mid-2010s, the first glimmers of change appeared. The gig economy took off, offering side hustles that could supplement meager salaries, while fintech apps made saving and investing more accessible than ever. Yet, the average net worth of 20 year olds remained stubbornly low. A 2016 Federal Reserve study found that the median net worth for young adults was just $10,000—far below what previous generations had at the same age. The problem wasn’t just debt; it was the erosion of traditional pathways to wealth. Homeownership, once a rite of passage, was now out of reach for most, and retirement accounts were a distant thought. The shift was also cultural. Social media amplified the pressure to appear financially successful, even as economic reality lagged. Influencers flaunted side hustles and "hustle culture," while the average 20 year old struggled to afford groceries without dipping into credit. The disconnect between perception and reality became a defining feature of this generation’s financial journey.The Turning Point
The pandemic acted as a catalyst, accelerating trends already in motion. Lockdowns disrupted careers, but they also forced a reckoning with financial priorities. Many 20 year olds who had been living at home or relying on gig work found themselves with more time—and more awareness—of their financial situation. The average net worth of 20 year olds didn’t skyrocket, but the conversation around personal finance did. Budgeting apps saw surges in downloads, and discussions about student debt cancellation gained mainstream traction. What changed wasn’t just behavior—it was the economic landscape. Wages for young workers finally began to rise, albeit modestly, while inflation and housing costs continued their upward spiral. The gap between the average net worth of 20 year olds and their parents’ net worth at the same age grew wider, but so did the tools available to bridge it. Employers started offering student loan repayment assistance, and student debt forgiveness became a political talking point. The turning point wasn’t a sudden shift, but a slow realization that the old rules no longer applied."You’re not failing if you’re not rich at 20. You’re just starting." — A financial planner working with Gen Z clients

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2008–2012 | Post-recession stagnation; student debt surges, wages flatline. The average net worth of 20 year olds plummets for many. |
| 2013–2016 | Gig economy emerges; side hustles become necessary for survival. Financial literacy tools (apps, YouTube) gain traction. |
| 2017–2019 | Stock market boom, but housing costs rise faster than wages. The average net worth of 20 year olds remains low, but some benefit from early investing. |
| 2020–2022 | Pandemic forces financial reckoning; stimulus checks provide temporary relief. Student debt forgiveness debates intensify. |
| 2023–Present | Inflation eats into savings; remote work options persist. The average net worth of 20 year olds stabilizes but remains uneven across demographics. |
Lessons From the Journey
- Debt is the new normal. Student loans and credit card debt are common, reshaping what "starting out" looks like.
- Side hustles are survival tools, not just extra income. Many 20 year olds treat them as financial lifelines.
- Homeownership is delayed—or abandoned. The average net worth of 20 year olds rarely includes property, a stark contrast to past generations.
- Financial education is patchy. Those who learn early (through family, apps, or mentors) fare better than those who don’t.
Where Things Stand Today
The average net worth of 20 year olds today is a study in contrasts. For those in well-paying fields—tech, healthcare, finance—early investing and side income can push their net worth into the five figures. But for the majority, especially in service industries or with student debt, the number hovers around $5,000 to $10,000. The pandemic’s economic fallout and inflation have delayed progress, but so too have cultural shifts: fewer young adults see homeownership as a priority, and retirement savings often take a backseat to immediate needs. What’s clear is that the traditional arc of financial growth—save, invest, own—has been disrupted. The average net worth of 20 year olds is no longer a predictor of future success; it’s a snapshot of a generation navigating uncharted territory. The question isn’t just how much they have, but how they’ll adapt as the economy continues to evolve.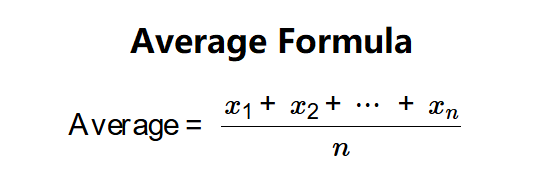
Conclusion
The story of the average net worth of 20 year olds is more than a financial metric—it’s a barometer of economic health. It reveals how debt, wages, and opportunity intersect, and how each generation’s starting point shapes its trajectory. For today’s young adults, the path to wealth is longer, more uncertain, and far more dependent on external factors than it was for their parents. Yet, in the tools they’ve adopted—from micro-investing to financial communities—they’re rewriting the rules. The numbers may be modest, but the resilience is undeniable. The average net worth of 20 year olds today isn’t just about dollars and cents; it’s about the choices they’re making in an economy that demands flexibility, creativity, and grit.Comprehensive FAQs
Q: What’s the average net worth of 20 year olds in the U.S.?
The Federal Reserve’s most recent data suggests the median net worth for young adults (ages 18–24) is around $10,000, though this varies widely by income, education, and location. Urban areas and high-cost states typically see lower averages due to housing and living expenses.
Q: How does student debt impact the average net worth of 20 year olds?
Student loans are a major drag. A 2023 report found that young adults with bachelor’s degrees but no savings often have negative net worth due to debt, while those without degrees may have lower debt but also lower earning potential. The average 20 year old with student loans can expect their net worth to grow more slowly in their early 20s.
Q: Can side hustles improve the average net worth of 20 year olds?
Absolutely—but it depends on how the income is managed. Freelancing, gig work, or passive income streams can boost savings, but many use extra earnings to cover essentials rather than invest. Those who treat side hustles as long-term assets (e.g., reinvesting profits) see faster growth in their net worth.
Q: Does where you live affect the average net worth of 20 year olds?
Yes. Cost of living plays a huge role. In cities like New York or San Francisco, the average net worth of 20 year olds is often negative due to rent and student debt. In lower-cost areas or with family support, young adults may build modest savings sooner. Remote work has blurred some of these lines, but geography still matters.
Q: Is the average net worth of 20 year olds getting better or worse?
It’s stabilizing but not improving dramatically. Post-pandemic wage growth helped, but inflation and housing costs offset gains. The long-term outlook depends on policy changes (e.g., student debt relief) and whether young adults can access higher-paying jobs. For now, progress is slow and uneven.
Q: What’s the biggest mistake 20 year olds make with their net worth?
Ignoring small wins. Many focus on big goals (like buying a house) without building emergency funds or paying down high-interest debt first. Others underestimate the power of compound interest by not starting to invest early. The average net worth of 20 year olds suffers when they prioritize lifestyle over financial foundation.
