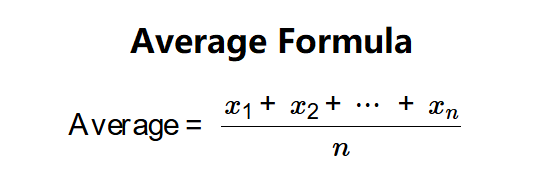
The Complete Overview of the Average 401k Balance for a 60-Year-Old
The most cited figures place the average 401k balance for a 60-year-old around $200,000, according to recent Vanguard and Fidelity reports. However, this number is skewed upward by outliers—those with high six-figure balances or early retirees who’ve aggressively saved. The median balance, a better indicator of typical savings, hovers closer to $150,000, revealing that half of all 60-year-olds have less than this amount. This disparity underscores why financial advisors emphasize median over mean when discussing retirement readiness. The gap between these figures isn’t just statistical; it’s a symptom of how wealth accumulates—or fails to—over a lifetime. Regional and income-based variations further complicate the narrative. In high-cost-of-living areas like California or New York, even a robust 401k may not stretch far enough in retirement, forcing many to rely on additional income streams. Meanwhile, in states with lower living costs, the same balance might provide greater security. The average 401k balance for a 60-year-old also varies by industry: tech workers and finance professionals tend to have higher balances due to higher salaries and employer matching, while service-sector employees often lag behind. These differences highlight the role of structural factors in shaping retirement outcomes.Historical Background and Evolution
The 401k’s rise from a niche tax-deferred savings vehicle to the cornerstone of retirement planning began in the 1980s, when Congress passed the Revenue Act of 1978, which allowed employers to offer 401k plans as an alternative to pensions. By the time the first wave of baby boomers hit 60 in the late 1990s, the average 401k balance for a 60-year-old was a fraction of what it is today—often under $50,000, adjusted for inflation. The shift from defined-benefit to defined-contribution plans meant that retirement security became increasingly tied to individual savings habits and market performance. The turn of the millennium brought two seismic events that reshaped these balances. The dot-com bubble burst in 2000, followed by the Great Recession of 2008, which wiped out trillions in retirement savings. For those turning 60 in the early 2010s, the average 401k balance for a 60-year-old was still recovering, often sitting 20–30% below pre-2008 peaks. The subsequent bull market of the 2010s, however, allowed later cohorts to rebound—though not all equally. The SECURE Act of 2019 further altered the landscape by raising the required minimum distribution age to 72 and expanding access to part-time workers, potentially boosting future balances for younger employees.Core Mechanisms: How It Works
At its core, a 401k functions as a tax-advantaged savings account, where employees contribute a portion of their paycheck before taxes, reducing their taxable income. Employers often match contributions up to a certain percentage—typically 3–5%—which acts as a forced savings mechanism. For a 60-year-old, the balance reflects decades of compounding, employer matches, and market fluctuations. The average 401k balance for a 60-year-old is influenced by three key variables: contribution limits (which have increased over time), investment performance, and the number of years of participation. Withdrawals are restricted until age 59½ to avoid penalties, though hardship withdrawals are permitted under certain conditions. Roth 401ks, which use after-tax contributions, offer tax-free withdrawals in retirement—a critical advantage for those expecting higher tax rates later. The average 401k balance for a 60-year-old also depends on whether they’ve rolled over previous employer plans or left money in old accounts. Consolidation can simplify management but may limit investment options. For those nearing retirement, the balance becomes a critical input in withdrawal strategies, such as the 4% rule, which suggests that withdrawing 4% annually can sustain a portfolio for 30 years.Key Benefits and Crucial Impact
The average 401k balance for a 60-year-old is more than a line item on a financial statement; it’s a determinant of financial freedom in later years. For those who’ve contributed consistently, it can provide a steady income stream, reducing reliance on Social Security or part-time work. The tax-deferred growth means that contributions and earnings accumulate without annual taxation, allowing balances to swell over time. Employer matches act as a multiplier effect, effectively increasing contributions without additional effort. Even for those with modest balances, the average 401k balance for a 60-year-old can serve as a foundation for other retirement assets, such as IRAs or real estate investments. Yet the impact isn’t uniform. Low-income workers, who may not have access to employer matches or face higher fees in target-date funds, often see their balances lag. The average 401k balance for a 60-year-old in this group may not cover basic living expenses, forcing them into precarious financial positions. For women, who tend to have lower lifetime earnings and longer lifespans, the average balance is often 20–30% lower than that of men, according to Transamerica studies. These disparities highlight the need for targeted policies, such as automatic enrollment in 401k plans or increased contribution limits for lower earners."Retirement isn’t an event; it’s a process. The average 401k balance for a 60-year-old is just one piece of the puzzle—how it’s managed in the next 20 years will define whether it’s a safety net or a springboard." — CFP Board Center for Financial Planning
Major Advantages
- Tax deferral: Contributions reduce taxable income, lowering annual tax bills.
- Employer matching: Free money that compounds over decades, often doubling contributions.
- Compound growth: Balances grow tax-free until withdrawal, accelerating wealth accumulation.
- Flexibility: Options to invest in stocks, bonds, or target-date funds tailored to risk tolerance.
- Withdrawal options: Structured withdrawals can provide income without depleting the principal.
- Legacy planning: Remaining balances can be passed to heirs with tax advantages.

Comparative Analysis
| Factor | Impact on Average 401k Balance for a 60-Year-Old |
|---|---|
| Income Level | Top 20% earners: Balances often exceed $500,000; bottom 20% may have under $50,000. |
| Employment Stability | Tenured employees with consistent matches outpace those who job-hopped frequently. |
| Market Timing | Those who retired post-2008 may have balances 15–25% lower than peers who retired in the 2010s. |
| Plan Type | Roth 401ks grow faster for high earners expecting higher taxes in retirement. |
Future Trends and Innovations
The average 401k balance for a 60-year-old is evolving alongside shifts in the workforce and investment strategies. The rise of automated advisory tools, such as robo-advisors within 401k platforms, is democratizing access to professional-grade portfolio management. Younger workers today are more likely to have access to employer matches and higher contribution limits, which could translate to larger balances for the next generation of 60-year-olds. However, the growing gig economy may reduce participation in traditional 401k plans, as many freelancers lack employer-sponsored options. Innovations like mega backdoor Roth contributions—where high earners contribute after-tax dollars to their 401k—are allowing some to accelerate savings, but these strategies are inaccessible to the average worker. The average 401k balance for a 60-year-old may also be influenced by new retirement models, such as phased retirement or part-time work in later years. As longevity increases, the balance must stretch further, making withdrawal strategies and healthcare costs critical considerations. The challenge for policymakers and employers is ensuring that the average balance isn’t just a number but a viable path to retirement security.
Conclusion
The average 401k balance for a 60-year-old is a snapshot of a lifetime of financial decisions, economic conditions, and systemic advantages—or disadvantages. While the median balance suggests many are still playing catch-up, the outliers remind us that retirement outcomes are far from predetermined. The data underscores the need for proactive planning, whether through catch-up contributions, Roth conversions, or diversifying income streams. For financial advisors, this demographic is a reminder that retirement readiness isn’t about hitting a benchmark but about building resilience against an uncertain future. The conversation around the average 401k balance for a 60-year-old must extend beyond numbers to address equity, education, and policy. Without interventions, the gap between those who retire comfortably and those who struggle will only widen. The question isn’t just how much someone has saved but how they’ll use it—and whether it’s enough to redefine retirement from a necessity to an opportunity.Comprehensive FAQs
Q: What’s the difference between the average and median 401k balance for a 60-year-old?
A: The average (mean) balance is inflated by high-earning outliers, while the median represents the middle value—half of 60-year-olds have less than this amount. For example, the average may be $200,000, but the median could be $150,000, indicating that many are saving less than the headline suggests.
Q: How does the average 401k balance for a 60-year-old compare to those in their 50s?
A: Balances typically grow significantly in the decade before 60 due to catch-up contributions (allowing $7,500/year after age 50). A 50-year-old’s average balance might be $120,000, while a 60-year-old’s jumps to $200,000—assuming consistent contributions and market growth.
Q: Can I withdraw from my 401k at 60 without penalties?
A: Withdrawals before 59½ incur a 10% early withdrawal penalty, though exceptions exist for hardships or specific plans like the Rule of 55 (allowing penalty-free withdrawals if you leave your job at 60). After 60, withdrawals are permitted but may trigger taxes.
Q: How does divorce affect the average 401k balance for a 60-year-old?
A: Divorce can split 401k balances as part of marital assets, often through a Qualified Domestic Relations Order (QDRO). This may reduce the balance but preserves tax-advantaged status. Without proper division, one spouse could lose access to a significant portion of retirement savings.
Q: Should I roll over my 401k when changing jobs at 60?
A: Rolling over to an IRA or new employer’s plan can simplify management and avoid required minimum distributions (RMDs) until age 73. However, consider fees, investment options, and withdrawal rules—some 401ks offer loan provisions that IRAs don’t.
Q: How does the average 401k balance for a 60-year-old vary by state?
A: High-income states like New York, California, and Massachusetts see averages near $250,000, while lower-income states like Mississippi or West Virginia may average $120,000–$150,000. Cost of living and wage disparities drive these differences.
Q: What’s the 4% rule, and how does it relate to the average 401k balance for a 60-year-old?
A: The 4% rule suggests withdrawing 4% annually from retirement savings to sustain the balance for 30 years. For a $200,000 balance, this means $8,000/year—but adjustments may be needed based on market conditions, healthcare costs, or inflation.
