
The Complete Overview of How to Fill Out Statement of Net Worth New York State
New York’s legal framework treats net worth statements as critical evidence, particularly in family law and commercial disputes. The Uniform Rules for the Trial Courts (22 NYCRR § 202.16) explicitly require full disclosure of financial particulars, with penalties for falsification under Penal Law § 175.10 (false instrument). Courts in New York often rely on these statements to determine equitable distribution in divorces or to assess damages in breach-of-contract cases. Unlike federal filings, which may tolerate broader estimates, New York’s local rules demand specificity—down to the valuation date and methodology. The document’s structure varies by context. In divorce proceedings, for example, Domestic Relations Law § 236(B)(5-a) mandates that both parties submit sworn financial disclosures, including net worth statements, within 45 days of service. For business disputes, the Civil Practice Law and Rules (CPLR § 3121) may require similar disclosures to prevent fraudulent transfers. The key difference lies in the burden of proof: in divorce cases, the court assumes the statement is accurate unless challenged; in civil litigation, the plaintiff often bears the responsibility to prove discrepancies.Historical Background and Evolution
The modern net worth statement in New York traces its roots to 19th-century equity law, when courts began requiring transparency in property divisions. The Matrimonial Asset and Debt Distribution Act (MADDA) of 1980 formalized these expectations, aligning New York with other states in treating marital assets as jointly owned—unless proven otherwise. This shift forced spouses to disclose assets with unprecedented granularity, as judges could no longer rely on vague affidavits. The 21st century brought digital assets into the mix. New York became one of the first jurisdictions to address cryptocurrency in divorce cases after a 2014 ruling (Matter of Leb v. Leb), where Bitcoin holdings were treated as marital property. Today, FinCEN guidelines and NY State Tax Law § 605 further complicate filings, as virtual currencies must be valued at their fair market value on the date of separation—not purchase price. This evolution underscores why how to fill out statement of net worth New York State now requires expertise in both traditional finance and emerging asset classes.Core Mechanisms: How It Works
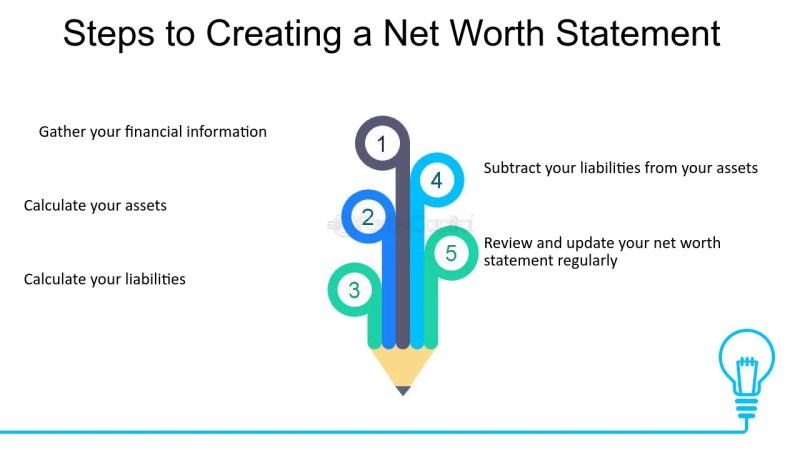
The document itself is a two-part exercise: listing assets and liabilities, then calculating the net difference. Assets include everything from primary residences to 401(k) balances, while liabilities cover mortgages, student loans, and even unpaid child support. The challenge lies in valuation consistency. Real estate, for example, must be appraised within 90 days of filing, using either a licensed appraiser’s report or a comparable market analysis (CMA) from a realtor. For business interests, goodwill and inventories often require forensic accountants to distinguish between personal and corporate value. Income streams complicate matters further. Alimony or maintenance payments must be listed as both assets (future receivables) and liabilities (ongoing obligations). Self-employed individuals face additional hurdles, as courts expect three years of tax returns to verify reported income. The New York State Department of Taxation and Finance provides templates, but local family courts often reject generic forms, insisting on jurisdiction-specific disclosures. This is why many attorneys advise clients to use court-approved templates or consult a financial forensic specialist before submission.Key Benefits and Crucial Impact
Accurate net worth statements serve as the foundation for fair legal outcomes. In divorce cases, they determine equitable distribution of assets, which in New York defaults to a 50/50 split unless one spouse can prove unequal contributions. For high-net-worth individuals, this can mean the difference between retaining a multimillion-dollar portfolio or losing half in settlements. Even in non-contentious divorces, precise disclosures prevent future disputes over hidden assets—such as offshore accounts or life insurance policies named as beneficiaries. Beyond divorce, these statements play a role in estate planning and business litigation. A will contest, for instance, may hinge on whether the decedent’s net worth matches the assets listed in the estate. Similarly, in fraudulent conveyance cases, prosecutors rely on pre-litigation net worth statements to prove asset transfers were intended to defraud creditors. The New York State Unified Court System has seen cases where inaccurate statements led to sanctions under CPLR § 3126, including fines or even contempt charges.“A net worth statement isn’t just paperwork—it’s a legal contract with the court. If you lie, you’re not just risking your case; you’re risking your credibility in future proceedings.” — Hon. Margaret A. Chan, NY Family Court Judge (Ret.)
Major Advantages
- Legal compliance: Avoids penalties under Penal Law § 175.10 for falsification, which can include jail time in extreme cases.
- Asset protection: Accurate valuations prevent disputes over hidden wealth, such as trust funds or art collections, which are common in New York’s high-asset divorces.
- Negotiation leverage: Precise disclosures force transparency, often leading to faster settlements when both parties trust the financial data.
- Tax implications: Correctly classified assets (e.g., primary residence vs. rental property) affect capital gains taxes and step-up basis rules.
Comparative Analysis
| New York State Requirements | Other Jurisdictions (e.g., California, Florida) |
|---|---|
| Mandatory for divorce (Domestic Relations Law § 236), business disputes (CPLR § 3121), and estate cases. | California requires Family Code § 2104 disclosures but allows broader estimates for small assets. Florida’s § 61.08 focuses on income verification. |
| Valuation must reflect market conditions as of filing date; appraisals required for real estate over $500K. | Texas permits appraiser discretion unless contested, while Illinois requires independent appraisals only for assets over $1M. |
| Digital assets (crypto, NFTs) must be disclosed with blockchain transaction histories if valued over $10K. | Massachusetts treats crypto as personal property but lacks specific valuation guidelines, leading to more litigation. |
| Failure to disclose can result in sanctions, contempt charges, or voided settlements under NYCRR § 202.16. | Florida’s § 61.13 allows judges to impute income from undisclosed assets, but penalties are less severe than in NY. |
Future Trends and Innovations
The rise of AI-driven financial analysis is poised to reshape how net worth statements are prepared. Tools like BlackLine and CaseWare already automate asset classification and discrepancy detection, reducing human error in high-volume cases. However, New York courts remain skeptical of fully automated valuations, particularly for illiquid assets like private equity or fine art. Judges continue to prefer human expert testimony for complex holdings. Another shift is the increasing scrutiny of passive income. With remote work and digital nomadism on the rise, New York courts are grappling with how to classify royalties, licensing fees, and affiliate income—especially when earned outside the state. The New York State Bar Association has issued advisory opinions suggesting that all global income must be disclosed, regardless of where it’s generated. This trend aligns with OECD’s Common Reporting Standard, which New York has adopted to combat tax evasion.
Conclusion
Filling out a net worth statement in New York is not a procedural formality—it’s a high-stakes financial audit with legal consequences. The document’s precision directly impacts divorce settlements, business disputes, and even criminal cases. Whether you’re a high-net-worth individual, a small business owner, or a divorcing spouse, the rules are clear: accuracy is non-negotiable, and transparency is enforced. The best approach? Treat the process as a collaborative effort between legal counsel and financial experts. Courts in New York increasingly expect third-party verification for assets over $250,000, making DIY filings a risky gamble. For those navigating how to fill out statement of net worth New York State, the message is simple: understand the rules, gather the evidence, and leave nothing to chance.Comprehensive FAQs
Q: What happens if I make a mistake on my New York net worth statement?
Mistakes can lead to sanctions under CPLR § 3126, including fines, delayed proceedings, or even contempt charges if the error is willful. Courts may also impute income from undisclosed assets, effectively penalizing you twice—once for the missing information and again through financial penalties. Always verify with a certified public accountant (CPA) or forensic accountant before filing.
Q: Do I need an appraiser for my primary residence?
Yes, if the property is valued at over $500,000. New York courts require licensed appraisals or comparable market analyses (CMAs) to ensure fair valuation. For lower-value homes, a realtor’s CMA may suffice, but judges scrutinize these closely in contested cases. Never rely on Zillow estimates—they’re inadmissible in court.
Q: How should I handle cryptocurrency in my net worth statement?
List all digital assets with their fair market value on the filing date, backed by blockchain transaction histories or exchange records. If the total exceeds $10,000, courts may require a forensic accountant’s report to distinguish between personal and business holdings. Failure to disclose crypto can trigger tax evasion investigations under NY Tax Law § 605.
Q: Can I exclude retirement accounts like a 401(k) or IRA?
No. All retirement accounts must be disclosed, including 401(k)s, IRAs, pensions, and annuities. The value is typically the current account balance, but courts may adjust for vesting schedules or loan balances. In divorce cases, these assets are often subject to equitable division, so omitting them risks asset forfeiture or post-judgment enforcement actions.
Q: What if my spouse refuses to provide financial documents?
File a motion to compel disclosure under Domestic Relations Law § 236(B)(5-a). Courts can order subpoenas for bank records, tax returns, or business filings. If your spouse still resists, the judge may impute income based on their lifestyle or sanction them for contempt. Document all attempts to obtain records—this strengthens your case.
Q: Are there templates I can use for my net worth statement?
New York’s Unified Court System provides generic templates, but local family courts often reject them. Instead, use forms approved by your county’s court clerk or consult your attorney for jurisdiction-specific versions. For high-net-worth cases, custom financial disclosures prepared by a CPA or forensic accountant are preferred to avoid rejection.
Q: How often do I need to update my net worth statement?
In divorce cases, updates are required annually or upon major financial changes (e.g., job loss, inheritance, or asset sale). For business litigation, courts may demand quarterly updates if the case drags on. Always check the court’s standing orders—some jurisdictions require real-time disclosures for assets over $1M.
Q: What if I own a business? How do I value it?
Business valuations require three methods: income approach (cash flow projections), market approach (comparable sales), and asset approach (net book value). Courts favor independent appraisals from ABV-certified valuators. For S-corps or LLCs, disclose owner’s equity, retained earnings, and goodwill. Undervaluing a business can lead to fraudulent transfer claims under Debtor and Creditor Law § 273.
Q: Can I challenge my spouse’s net worth statement?
Yes. File a motion to compel further disclosure or a motion for sanctions if the statement is incomplete or misleading. Courts often order independent audits or depositions to verify claims. If you suspect hidden assets, subpoena bank records, tax returns, or offshore account statements. New York courts have voided settlements based on undisclosed wealth.
Q: What’s the best way to prepare for a net worth statement in NY?
1. Gather documents: Tax returns (last 3 years), bank statements, investment portfolios, real estate deeds, and business records. 2. Consult experts: A CPA for valuations, a forensic accountant for complex assets, and an attorney familiar with NY’s Domestic Relations Law. 3. Avoid red flags: No cash-only transactions, untraceable assets, or last-minute transfers. 4. File early: Delays can extend proceedings, and late submissions may be automatically rejected.
