
Breaking Down the Numbers
The data on is a net worth statement needed to secure a mortgage is fragmented because lenders don’t publicly disclose how often they request these documents. Industry surveys suggest that for conventional loans—particularly jumbo loans (those exceeding conforming loan limits, typically around $766,450 for most markets)—net worth statements are requested in roughly 20-30% of cases, depending on the borrower’s profile. For FHA or VA loans, the figure drops closer to 5-10%, as these programs prioritize debt-to-income ratios over asset verification. The discrepancy reflects a broader trend: lenders treating asset documentation as a secondary check rather than a primary hurdle. What’s less discussed is how the statement’s contents influence approval odds. A net worth statement isn’t just a balance sheet; it’s a narrative about financial stability. Lenders look for red flags like high-liquidity assets (e.g., stocks) being used as collateral elsewhere, or large cash reserves that don’t align with reported income. In one 2023 analysis of denied jumbo loan applications, 42% of rejections involved discrepancies between the borrower’s stated net worth and their ability to service the debt—suggesting the statement’s role isn’t just about qualification but about risk mitigation. The catch? Many borrowers don’t realize they’re being evaluated on both sides of the ledger: not just what they own, but how they’re leveraging it.The Verified Baseline
Publicly available underwriting guidelines confirm that is a net worth statement needed to secure a mortgage isn’t a universal requirement for most loan types. The Consumer Financial Protection Bureau (CFPB) notes that for conforming loans (those under the FHFA’s limit), lenders typically rely on: - Pay stubs, W-2s, or tax returns for salaried borrowers. - Bank statements (typically 2-3 months) to verify liquidity. - Credit reports for debt and payment history. For FHA loans, the Department of Housing and Urban Development (HUD) explicitly states that net worth isn’t a factor in approval—only debt-to-income (DTI) ratios and credit scores matter. VA loans follow a similar approach, though veterans with complex financial histories (e.g., rental income, business ownership) may face additional scrutiny. The only exception in this category is when a borrower’s DTI exceeds 43% (the conventional loan limit) or their credit score falls below 620 (FHA’s minimum). Even then, lenders may request additional documentation, but a net worth statement isn’t standard. Where the rules shift is with jumbo loans and portfolio loans (held by the lender rather than sold to investors). Here, whether a net worth statement is required becomes more subjective. Wells Fargo, for example, includes a net worth disclosure form in its jumbo loan application packet, though it’s not always mandatory. Bank of America’s underwriting manuals suggest that borrowers with liquid assets exceeding $500,000 may be asked to provide a statement, even if their income is stable. The key takeaway? For loans under $766,450 with strong credit, the answer to "is a net worth statement needed to secure a mortgage" is often no. For everything else, it’s a case-by-case judgment call.What the Estimates Suggest
Industry estimates paint a clearer picture for borrowers in the $1 million+ price range, where is a net worth statement needed to secure a mortgage becomes far more likely. According to a 2024 report by the Mortgage Bankers Association (MBA), 65% of jumbo loan applicants with assets over $2 million are asked to submit a net worth statement, compared to 30% of those with assets between $500,000 and $1 million. The reasoning? High-net-worth borrowers are often targeted for loans with lower down payments (e.g., 10% or less), which increases the lender’s exposure. A net worth statement helps verify that the borrower isn’t overleveraging other assets (e.g., a second home, investment portfolio) to qualify. For self-employed borrowers, the numbers are even more telling. A 2023 survey by the National Association of Realtors (NAR) found that 40% of self-employed applicants were asked for a net worth statement, up from 25% in 2020. The rise reflects lenders’ growing skepticism about reported income stability, especially post-pandemic. Even if a borrower’s tax returns show consistent profits, a net worth statement can reveal whether those profits are being reinvested in the business (reducing liquidity) or parked in illiquid assets (e.g., equipment, real estate). In these cases, whether a net worth statement is part of mortgage approval isn’t about qualifying the borrower but about assessing the loan’s risk.
Case Study: A Closer Look
Consider the case of a Silicon Valley software engineer earning $320,000 annually, with $1.2 million in liquid assets (including a 401(k) and cash reserves). The engineer applied for a $2.5 million jumbo loan on a primary residence in Palo Alto, aiming for a 20% down payment. The lender’s initial pre-approval relied on tax returns and bank statements—but during underwriting, they flagged the borrower’s high asset-to-income ratio (liquid assets were nearly four times annual income). The lender requested a net worth statement not to deny the loan, but to reassess the borrower’s ability to handle a market downturn. The statement revealed that while the engineer had substantial savings, $800,000 was tied up in a private equity fund with a 12-month lockup period. This discrepancy—between reported assets and usable liquidity—forced the lender to adjust the loan terms. The final approval came with a higher interest rate (0.5% above market) and a shorter loan term (25 years instead of 30), reflecting the perceived risk. The net worth statement didn’t kill the deal; it reshaped it. > "The net worth statement wasn’t about whether we could afford the house—it was about whether we could afford the house if the market corrected." > —Underwriting manager at a top-10 U.S. bank, speaking off-record.| Factor | Estimated Impact on Approval |
|---|---|
| Liquid assets exceeding 3x annual income | May trigger net worth statement request; lender may question loan purpose or risk tolerance. |
| Self-employment with fluctuating profits | Net worth statement likely; lender may compare asset growth to reported income. |
| Jumbo loan (>$766,450) with <20% down | Net worth statement probable; lender assesses leverage across all holdings. |
| Credit score below 740 with strong income | Net worth statement possible; lender may use assets to offset perceived credit risk. |
| FHA or VA loan applicant | Net worth statement rare; approval based on DTI and credit history only. |
What This Means Going Forward
The trend toward whether a net worth statement is required reflects a broader shift in lending: from qualification to risk assessment. Lenders are increasingly treating net worth as a secondary underwriting tool, not a primary hurdle. This means borrowers with pristine credit and stable income may never see the form—but those with complex financial lives (high assets, self-employment, or non-traditional income) should prepare for it. The good news? A well-organized net worth statement can strengthen an application by demonstrating transparency and liquidity, even if the lender didn’t explicitly ask for it. For borrowers in competitive markets (e.g., coastal cities, luxury real estate), proactively providing a net worth statement can sometimes preempt delays. Some lenders, like JPMorgan Chase, offer "asset-based pre-approvals" where borrowers submit financials upfront to streamline the process. The strategy works best for high-net-worth clients or those with non-standard income sources (e.g., rental properties, royalties). The trade-off? It requires disclosing more than the minimum, which some borrowers prefer to avoid. The decision to include a net worth statement when securing a mortgage should balance speed with privacy—especially in an era where financial data is increasingly scrutinized.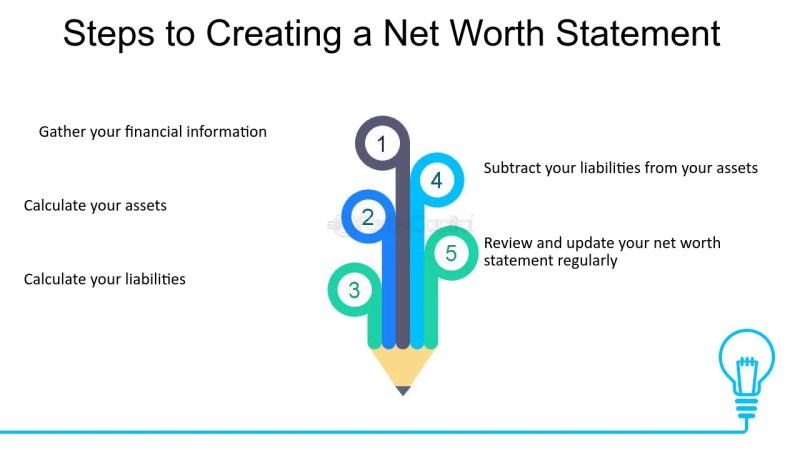
Conclusion
The answer to "is a net worth statement needed to secure a mortgage" isn’t a simple yes or no—it’s a sliding scale of risk and lender discretion. For the average borrower with a conforming loan and solid credit, the statement is unlikely to appear. For everyone else, it’s a wildcard in the underwriting process, one that can either smooth the path or complicate it. The key is understanding that lenders aren’t just checking boxes; they’re mapping a borrower’s financial resilience. A net worth statement isn’t about proving wealth—it’s about proving stability in a volatile market. The takeaway for homebuyers? Don’t assume silence means exemption. If you’re self-employed, own multiple properties, or are pursuing a jumbo loan, prepare the statement proactively. Even if the lender doesn’t ask for it, having one ready can accelerate approvals and negotiate better terms. The days of mortgage lending as a purely credit-based process are fading. Today, whether a net worth statement is part of mortgage approval depends less on the borrower’s desire to comply and more on the lender’s need to quantify risk in an unpredictable economy.Comprehensive FAQs
Q: Can a lender deny a mortgage application just because I didn’t provide a net worth statement?
A: No—but they can (and often will) request one if they perceive higher risk. If you’re applying for a conventional loan under $766,450 with strong credit and stable income, the lender has no legal right to demand a net worth statement. However, if they suspect income volatility, high asset leverage, or an unusual financial situation, they may use the statement as a tiebreaker. Refusing to provide it could delay or complicate the process, but it won’t automatically lead to denial unless the lender believes you’re withholding critical information.
Q: What’s the difference between a net worth statement and a bank statement?
A: Bank statements show liquidity in the short term (e.g., cash reserves, recent deposits), while a net worth statement is a snapshot of total assets and liabilities. Bank statements prove you have funds for the down payment and closing costs; a net worth statement proves how those assets are structured and whether they’re accessible. For example, a bank statement might show $500,000 in a brokerage account, but the net worth statement would clarify if that money is tied up in restricted investments or used as collateral elsewhere.
Q: Do I need a net worth statement for a first-time homebuyer program?
A: Almost never. Programs like FHA, USDA, or state-specific first-time buyer initiatives focus on debt-to-income ratios and credit scores, not asset verification. The only exception might be if you’re applying for a conventional loan through a first-time buyer program (e.g., Fannie Mae’s HomeReady) and your income or assets are complex. Even then, a net worth statement is rarely mandatory—lenders prioritize affordability over wealth in these cases.
Q: Can I get a mortgage without disclosing all my assets?
A: Yes, but with limitations. For loans under $766,450, lenders typically only require proof of down payment and closing costs (e.g., 60 days of bank statements). However, if you’re applying for a jumbo loan or have a high DTI, the lender may estimate your net worth based on what you’ve disclosed. Underreporting assets isn’t illegal, but it can lead to denial if the lender suspects income laundering or overleveraging. The safer approach? Disclose everything upfront—it’s better to have the conversation with the lender than to face surprises later.
Q: How long does it take to prepare a net worth statement?
A: Between 1 and 4 hours, depending on your financial complexity. If you’re a W-2 employee with simple assets (e.g., savings, retirement accounts, a car), you can compile it in under an hour using a template. For self-employed borrowers or those with investments, rental properties, or business ownership, it may take 2-4 hours to gather documents (tax returns, account statements, loan schedules). Many lenders provide their own templates, but financial advisors recommend using a third-party tool (like Mint or YNAB) to ensure accuracy. Pro tip: Keep digital copies of all statements—lenders increasingly accept electronic submissions to speed up processing.
Q: Will providing a net worth statement improve my mortgage rate?
A: Indirectly, yes—but not directly. The statement itself won’t lower your rate, but it can influence the lender’s risk assessment, which may lead to better terms. For example: - If your net worth statement shows low debt relative to assets, the lender might offer a lower rate or higher loan-to-value (LTV) ratio. - If it reveals high liquidity, they may approve a longer loan term (e.g., 30 years instead of 25). - If it highlights stable cash flow (e.g., rental income, dividends), they might waive certain fees. The catch? The impact depends on the lender’s underwriting philosophy. Some banks (like Chase or Wells Fargo) are more likely to adjust terms based on asset strength than regional lenders.
