The Short Answers
- The average net worth per decade accelerates after 40, but early decades often show slow growth due to student debt and career establishment.
- Geography matters: U.S. figures differ wildly from Europe or Asia, with housing costs being the biggest divider.
- Inflation distorts decade-to-decade comparisons—what seemed like progress in the 1980s might not hold up today.
- Outliers (inheritance, entrepreneurship, market timing) can skew averages—most people’s wealth follows a slower, steadier curve.
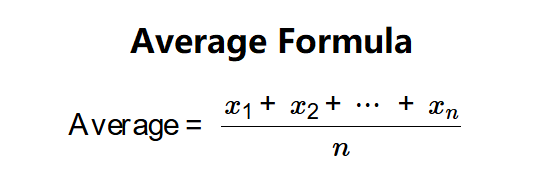
Deep Dive: The Full Picture
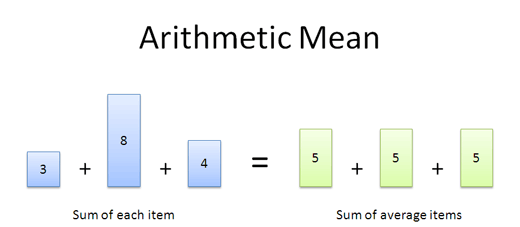
The average net worth per decade of life isn’t a fixed ladder but a series of plateaus and climbs, each shaped by external forces. Take the 1990s: a 30-year-old then might have had $50,000, but adjusted for inflation, that’s closer to $100,000 today. Yet the composition of that wealth changed. In 1995, homeownership was the primary driver; today, retirement accounts and investment portfolios dominate for those in their 50s. The shift reflects broader economic trends: the death of pensions, the rise of gig work, and the fact that today’s 30-year-olds are more likely to be burdened by student loans than their parents were by mortgages. The data also exposes a generational fault line. Millennials, now in their 40s, entered the workforce just as housing prices surged and wage stagnation set in. Their average net worth per decade in their 30s lags behind Gen X’s by roughly 20%. Boomers, meanwhile, benefited from a bull market in their 50s and 60s—something Gen Z may not replicate if interest rates stay elevated. The numbers aren’t just about age; they’re about era.The Context You Need
To understand average net worth per decade, you must first accept that averages lie. The median is often more telling: it splits the population in half. In 2022, the median net worth for a U.S. household headed by someone 35–44 was $120,000, while the average was $634,000—skewed upward by a few ultra-wealthy households. This disparity highlights how wealth concentrates over time. The top 10% of earners hold nearly 70% of all liquid assets, meaning most people’s progress is measured in increments, not leaps. Another layer is timing. Someone who inherits $500,000 at 40 will see their average net worth per decade spike artificially in their 40s, while a peer who builds wealth organically might take until their 50s to match that figure. The data doesn’t distinguish between these paths—it only shows the end result. This is why financial planners often focus on relative growth rather than absolute numbers. A 25-year-old with $20,000 might be on track if they’re saving aggressively, while a 55-year-old with $300,000 could be falling behind if they haven’t adjusted for inflation.The Mechanics
The mechanics of average net worth per decade boil down to three variables: income growth, asset appreciation, and debt management. Income is the most volatile. A software engineer’s earnings in their 30s might double by their 40s, while a retail worker’s stagnates. Asset appreciation—stocks, real estate, business equity—compounds over time, but only if you’re invested. The S&P 500’s average annual return of ~10% means a $10,000 investment at 25 could grow to $370,000 by 65. Debt, however, acts as a drag. Student loans or medical bills can erase decades of progress. A 40-year-old with $100,000 in student debt might have a net worth of $150,000, while a peer with no debt could have $400,000. The second half of life is where the math tilts in favor of those who’ve played the long game. Social Security benefits, pension payouts, and the sale of appreciated assets (like a home) become major wealth drivers. Yet this assumes stability. A 2020 study found that 28% of Americans over 50 had less than $50,000 in retirement savings—meaning their average net worth per decade in their 60s would be far lower than projections. The system rewards consistency, but it punishes disruptions.Details That Change the Picture
The average net worth per decade varies dramatically by marital status. Married couples typically see their net worth grow 30–50% faster than singles, thanks to combined incomes, shared expenses, and the ability to leverage dual careers. But this masks the reality that women, on average, earn 18% less than men—meaning their solo progress is slower. Race further complicates the picture. A Black household’s median net worth is $24,100 compared to $188,200 for a white household, a gap that widens with age. These disparities aren’t just about earnings; they’re about inheritance, discrimination in lending, and historical redlining that depressed property values in minority neighborhoods for generations. Then there’s geography. In San Francisco, a 45-year-old’s net worth might be inflated by a $1.5 million home, while in Detroit, the same age group’s median is closer to $120,000. Renters vs. homeowners tell an even starker story: homeowners’ net worth is 40x higher than renters’ at the same age. The average net worth per decade in a high-cost city like New York is often a mirage—what looks like growth is just keeping up with skyrocketing rents."Wealth isn’t just about how much you earn; it’s about how much you keep—and how long you keep it." — Edward N. Wolff, Professor of Economics at NYU and author of Wealth in America
| Age Bracket | Median Net Worth (U.S., 2022) |
|---|---|
| 25–34 | $80,000 (student debt often offsets gains) |
| 45–54 | $230,000 (peak homeownership years) |
| 65–74 | $300,000 (Social Security + asset liquidation) |

Conclusion
The average net worth per decade is less a destination and more a reflection of the rules you played by—or the ones that were stacked against you. It’s a tool for comparison, not a roadmap. What it does reveal is the power of time, the cost of delay, and the way systemic barriers can derail even the most disciplined savers. The numbers also underscore a harsh truth: most people’s wealth isn’t built in their 20s or 30s—it’s the cumulative result of decades of small, often invisible decisions. But averages are cold. The real story is in the individual trajectories—the single mother who saved $500/month for 30 years, the freelancer who weathered three recessions, the retiree who downsized to fund a grandchild’s education. The average net worth per decade is a starting point, not an endpoint. The question isn’t what the numbers say, but what they mean for you—and whether you’re willing to rewrite them.Comprehensive FAQs
Q: Why does net worth growth slow down in the 20s and 30s?
The early decades are often a net-negative for wealth due to student loans, early-career salaries, and the cost of establishing independence (rent, car payments, etc.). Even if you save aggressively, debt and lower earning potential can offset gains. By the late 30s, many hit a "wealth inflection point" where income growth outpaces expenses, but this varies by field—doctors and engineers typically see faster progress than service workers.
Q: How does divorce affect the average net worth per decade?
Divorce can reset decades of progress. Studies show couples’ combined net worth drops by 30–40% post-divorce, and single women over 50 see their net worth decline by 20% on average due to lower earnings and higher medical costs. The average net worth per decade for divorced individuals often stagnates in their 40s and 50s unless they remarry or inherit wealth. Alimony and child support can temporarily offset losses, but long-term, the financial impact is severe.
Q: Are there decades where net worth can decline?
Yes—particularly in the late 50s and early 60s, when medical expenses, long-term care costs, or market downtights (like 2008) can erode savings. Retirees who live on fixed incomes may see their net worth shrink by 10–15% annually in bad years. Even without crises, lifestyle inflation (travel, hobbies) can outpace Social Security adjustments. The average net worth per decade in retirement often reflects not growth, but survival.
Q: How does entrepreneurship skew these averages?
Entrepreneurship is the wild card. A successful startup founder’s net worth can jump from $100,000 to $10 million between ages 35 and 45—skewing the average net worth per decade upward. But 80% of startups fail, and many founders end up with less than they started. The data doesn’t capture the risk: the median entrepreneur’s net worth grows only 5% faster than a salaried peer’s, but the top 1% see gains 10x higher. This is why "average" is misleading—it hides the extreme volatility of self-employment.
Q: What’s the biggest myth about net worth progression?
The myth that average net worth per decade follows a smooth, predictable curve. In reality, it’s a series of plateaus punctuated by shocks—inheritance, layoffs, market crashes, or sudden windfalls. The data also ignores the "wealth illusion" of home equity: many homeowners assume their house is an asset, but if they downsize in retirement, that equity vanishes. The biggest mistake people make is assuming their peers’ progress is replicable without accounting for luck, timing, or access to capital.
