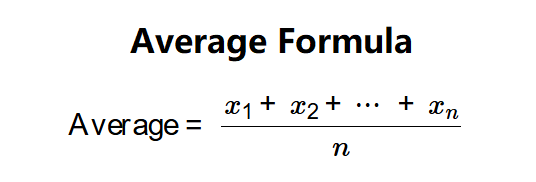
Breaking Down the Numbers
The average net worth by age 40 isn’t a single figure but a distribution shaped by demographics, geography, and economic conditions. For example, a 40-year-old in San Francisco faces a different calculus than one in Wichita: median home prices in the Bay Area can swallow a decade’s worth of savings, while rural markets may offer equity at a fraction of the cost. Even within cities, disparities emerge. A 2022 study by the Urban Institute found that Black households at this age had a median net worth of $24,100—less than 10% of white households’ $276,000. These aren’t outliers; they’re structural. The confusion often stems from conflating median and mean figures. While the median net worth by age 40 sits around $138,000 (per Fed data), the mean jumps to $727,000 due to a handful of ultra-high-net-worth individuals skewing the average. This distinction matters because most people operate near the median, not the mean. The implication? Average net worth by age 40 is less about hitting an arbitrary benchmark and more about navigating the gap between aspiration and feasibility.The Verified Baseline
Publicly available data from the Federal Reserve’s Survey of Consumer Finances provides the most reliable baseline. For households headed by someone aged 35–44, the median net worth in 2022 was $138,000, with liquid assets (cash, stocks, retirement accounts) accounting for roughly 40% of that total. Homeownership remains the single largest wealth driver: 65% of 40-year-olds own their primary residence, and those who do see their net worth inflated by equity—often the difference between a modest and a comfortable financial position. What’s less visible in the data is the role of inheritance and family wealth. A 2021 Pew Research analysis found that 36% of Americans aged 30–49 received some form of financial assistance from parents, whether through down payments, education funding, or direct gifts. This isn’t charity; it’s a wealth transfer mechanism that accelerates the average net worth by age 40 for those who benefit. For the 64% who don’t, the path to comparable wealth requires aggressive saving, asset appreciation, or both.What the Estimates Suggest
Private sector estimates—often derived from wealth management firms—paint a rosier picture but with critical caveats. Fidelity Investments, for instance, suggests that the average net worth by age 40 for its clients (a self-selected group with higher incomes) hovers around $600,000. This figure includes those with advanced degrees, high-earning professions, and access to employer-sponsored retirement plans. It’s not representative of the broader population, but it highlights how average net worth by age 40 varies by cohort. Industry analysts also emphasize the role of market timing. Someone who entered the workforce in 2008—during the Great Recession—faces a different trajectory than a peer who joined in 2018, benefiting from a decade of bull markets. A 2023 report by the Economic Policy Institute estimated that the net worth gap by age 40 between the top 10% and the bottom 90% had widened by 40% since 2000, largely due to asset price inflation favoring those who already owned homes or stocks. The takeaway? Average net worth by age 40 is as much about timing as it is about effort.
Case Study: A Closer Look
Consider the trajectory of a 40-year-old software engineer in Austin, Texas, who bought a $450,000 home at 30 with a 20% down payment. Their salary of $140,000 includes a $15,000 annual 401(k) match, and they’ve contributed an additional $10,000 to an IRA annually. Assuming a 7% average return on investments and a 3% home value appreciation, their net worth would likely exceed $750,000 by age 40—well above the median but below the top decile. The difference? They leveraged home equity, benefited from a strong local job market, and avoided student debt. Yet this scenario masks the fragility of such outcomes. A single job loss, medical emergency, or market correction could reset their progress. The average net worth by age 40 for someone in this position isn’t just a product of income; it’s a function of risk tolerance, liquidity buffers, and the ability to pivot when plans derail.“Net worth at 40 isn’t about the number—it’s about the options that number unlocks. A $500,000 portfolio might buy peace of mind, but a $2 million portfolio buys flexibility. The real question is: What trade-offs are you willing to make to bridge that gap?” — Wealth strategist and former BlackRock analyst (anonymous request)
| Factor | Estimated Impact on Net Worth by Age 40 |
|---|---|
| Homeownership (20% down at age 30) | +$300,000–$500,000 (equity + appreciation) |
| Employer 401(k) match ($15K/year) | +$250,000–$350,000 (assuming 7% returns) |
| Student debt ($30K at 5% interest) | −$50,000–$80,000 (opportunity cost + payments) |
| Side hustle (freelance income reinvested) | +$100,000–$200,000 (if compounded aggressively) |
What This Means Going Forward
The average net worth by age 40 serves as a reality check for those chasing aggressive financial goals. For the median earner, the focus must shift from emulating the top 1% to optimizing within their constraints. This means prioritizing liquidity over speculative assets, leveraging tax-advantaged accounts, and—crucially—protecting against downside risk. A single uninsured event (e.g., a $100,000 medical bill) can erase years of progress for someone with a $200,000 net worth. The data also underscores the importance of net worth growth strategies over one-off windfalls. Passive income streams, such as rental properties or dividend-paying stocks, become critical after 40, as they reduce reliance on labor income. Yet the most underrated factor remains time arbitrage: delaying gratification to accelerate compounding. Someone who saves $500/month from age 25 vs. age 35 will have nearly double the net worth by 40, all else equal.
Conclusion
The average net worth by age 40 is less a target and more a diagnostic tool—one that reveals where you stand relative to peers and where systemic advantages (or disadvantages) may be at play. For those below the median, the path forward isn’t about chasing impossible benchmarks but about stacking probabilities in their favor: homeownership, debt elimination, and consistent investing. For those above, the challenge shifts to preserving and growing wealth in an era of rising costs and market volatility. Ultimately, the conversation around net worth at this stage must move beyond numbers. It’s about resilience: the ability to absorb shocks, adapt to change, and redefine success on terms that aren’t dictated by averages. The goal isn’t to hit a specific figure—it’s to build a financial foundation that aligns with your values, not someone else’s milestones.Comprehensive FAQs
Q: Is the average net worth by age 40 realistic for someone earning $70K/year?
A: For a single earner in this bracket, the median net worth by age 40 ($138K) is achievable but requires disciplined saving (e.g., maxing a 401(k) match, avoiding lifestyle inflation). Homeownership and low debt are critical. Couples can accelerate progress through dual incomes and shared expenses.
Q: How does student debt impact the average net worth by age 40?
A: Student loans reduce net worth by their face value and opportunity cost. A 2023 Brookings analysis found that borrowers with $50K in debt at age 30 had a net worth by age 40 roughly 30% lower than non-borrowers, even with similar incomes. Aggressive repayment or refinancing can mitigate this.
Q: Can you outpace the average net worth by age 40 without high income?
A: Yes, but it demands extreme frugality and asset leverage. Examples include:
- Real estate: Buying a duplex and renting one unit.
- Side income: Reinvesting freelance earnings into index funds.
- Tax optimization: Maximizing HSAs and Roth IRAs.
Q: Does marriage or having kids significantly alter the average net worth by age 40?
A: Indirectly. Married couples often pool resources, accelerating homeownership or retirement savings. However, children introduce new expenses (childcare, education) that can delay wealth accumulation. Data shows married 40-year-olds have a net worth by age 40 ~20% higher than singles, but the gap narrows if child-related costs aren’t managed.
Q: Are there geographic areas where the average net worth by age 40 is higher?
A: Yes. States with strong job markets (e.g., Texas, Washington) and lower costs of living (e.g., Midwest) tend to see higher median net worths by 40. Coastal cities (NYC, SF) have higher averages but also higher barriers to entry. Rural areas often lag due to limited asset appreciation.
