
Breaking Down the Numbers
Net worth statements fail when they treat assets as monoliths. A Roth IRA isn’t just a number—it’s a tax-advantaged vehicle with withdrawal rules. A small business isn’t liquid; its value depends on earnings multiples or goodwill. Even cash isn’t equal: a high-yield savings account earns 4.2% APY, while a money market fund might yield 3.8%. These distinctions matter when calculating growth rates or planning liquidity. The process begins with creating a net worth statement that separates assets into three tiers: 1. Liquid (cash, CDs, brokerage accounts) 2. Illiquid but marketable (real estate, collectibles, private equity) 3. Non-marketable (pensions, intellectual property, heirlooms) Liabilities must be treated similarly. A variable-rate credit card debt at 22% APR isn’t the same as a fixed-rate mortgage at 3.5%. The former demands aggressive payoff strategies; the latter can be refinanced. Ignoring these nuances leads to statements that look neat but mislead.The Verified Baseline
Public records provide the foundation. Property values can be cross-checked with county assessor databases, while investment portfolios are verified via brokerage statements. For businesses, financial disclosures (if publicly traded) or audited statements (for LLCs) offer hard data. Even personal assets like jewelry can be appraised by third-party services like the American Society of Appraisers. The challenge lies in creating a net worth statement for assets without market prices. A rare first-edition book might fetch $5,000 on eBay, but its true value depends on provenance. Here, hedged language is critical: instead of listing "$5,000," note "estimated at $4,500–$5,500 based on comparable sales." This transparency prevents overinflation.What the Estimates Suggest
Where hard data ends, professional judgment begins. Real estate agents use comps to estimate home values, while art consultants rely on auction records. For private companies, multiples of EBITDA (earnings before interest, taxes, depreciation, and amortization) are standard—but these vary by industry. A tech startup might trade at 8x EBITDA, while a manufacturing firm could be valued at 4x. The danger isn’t estimation itself; it’s creating a net worth statement that assumes precision where none exists. A 2022 study by the National Association of Realtors found that 30% of homeowners overestimated their property’s value by 10% or more. Adjusting for this bias requires conservative rounding. If a home is worth $650,000, listing it as $630,000 accounts for potential appraisal gaps.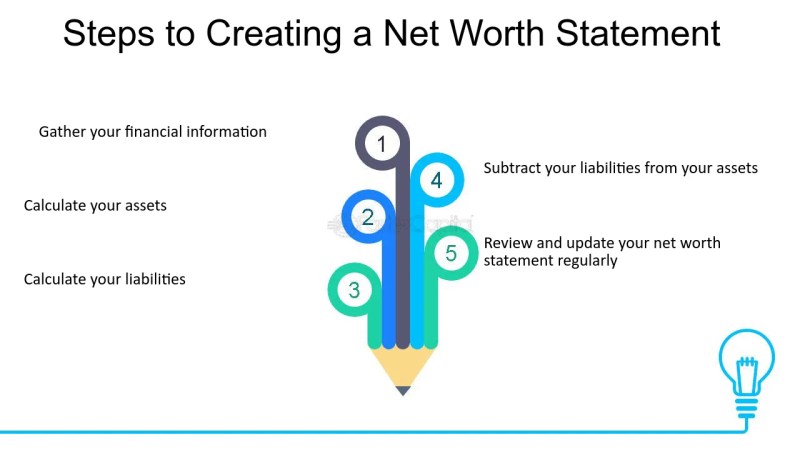
Case Study: A Closer Look
Consider a freelance graphic designer in their early 40s with: - A primary residence worth $450,000 (mortgage: $200,000) - $80,000 in a 401(k) (employer match: $15,000/year) - $12,000 in credit card debt at 18% APR - A side hustle generating $2,000/month in passive income Their net worth appears straightforward, but creating a net worth statement reveals hidden layers. The passive income stream—from digital products—has no liquid value unless sold. The credit card debt, if paid aggressively, could reduce net worth by $12,000 in 12 months. Meanwhile, the 401(k) grows at 7% annually, but withdrawals before 59½ incur penalties."Net worth is a snapshot, but cash flow is the movie. A high net worth with no income streams is like a yacht with no engine—it looks impressive until you try to move." — Jane Smith, Certified Financial Planner (CFP)
| Factor | Estimated Impact on Net Worth |
|---|---|
| Aggressive credit card payoff | Increase by ~$12,000 in 12 months (assuming no new debt) |
| 401(k) growth at 7% annualized | Add ~$5,600/year to net worth (pre-tax) |
| Side hustle liquidation (selling digital assets) | Potential gain of $50,000–$100,000 (highly speculative) |
What This Means Going Forward
For individuals, the shift is cultural. Tracking net worth monthly—like monitoring a health metric—reveals patterns. Did a stock market dip erase two years of savings? Did refinancing a mortgage free up cash flow? These insights drive decisions. Tools like Personal Capital or Mint automate the process, but manual reviews catch errors (e.g., duplicate transactions, missed liabilities). Institutions use net worth statements for risk assessment. Banks evaluate loan applications against them; investors analyze portfolio diversification. Even governments rely on them for policy—wealth taxes, for example, target net worth brackets, not income alone. The precision in creating a net worth statement determines whether a family qualifies for a mortgage or a business secures venture funding.
Conclusion
Net worth isn’t vanity. It’s a measure of financial health, resilience, and opportunity. Creating a net worth statement forces clarity: Are your assets working for you, or are you working for them? The best statements balance rigor with realism. They account for market fluctuations, tax implications, and personal goals—not just balance sheet numbers. The process isn’t about chasing a target. It’s about understanding the levers you control: debt reduction, asset allocation, income diversification. A net worth statement isn’t a report card; it’s a roadmap. Update it quarterly, adjust for life changes, and use it to ask the right questions. Because in finance, as in medicine, diagnosis comes before treatment.Comprehensive FAQs
Q: How often should I update my net worth statement?
Quarterly is ideal for most people, especially if you have variable income, fluctuating investments, or significant debt. High-net-worth individuals may update monthly to track large asset movements (e.g., real estate, private equity). Automated tools can simplify this, but manual reviews catch errors.
Q: Should I include sentimental items (e.g., heirlooms, art) in my net worth statement?
Yes, but only if they have verifiable value. Sentimental items without market data should be noted separately with a disclaimer (e.g., "Estimated value based on appraisal, not liquidation potential"). Overstating their worth distorts financial planning.
Q: How do I handle assets with fluctuating values (e.g., crypto, stocks)?
Use the most recent verified value at the time of the statement. For volatile assets like crypto, consider averaging the high/low over the past 30 days to avoid extreme swings. Never use hypothetical "peak" values—stick to current market prices.
Q: Does a net worth statement replace a budget?
No. A net worth statement is a snapshot of assets and liabilities, while a budget tracks cash flow. Together, they form a complete picture: your net worth shows what you own, and your budget shows how you’re using (or losing) it.
Q: Can I create a net worth statement if I have no assets or high debt?
Absolutely. A net worth statement with negative equity is still useful. It highlights liabilities to prioritize (e.g., high-interest debt) and sets a baseline for improvement. The goal isn’t to impress—it’s to inform.
Q: How do I account for assets I can’t easily sell (e.g., a business, pension)?
Estimate their value using professional methods:
- Businesses: EBITDA multiples or discounted cash flow (DCF) analysis
- Pensions: Present value of future payments (use a financial calculator)
- Intellectual property: Licensing potential or comparable sales
Q: Should I share my net worth statement with others (e.g., a financial advisor, spouse)?
Sharing depends on trust and purpose. A financial advisor needs it for planning; a spouse may need it for transparency. Never share unverified estimates—only statements with documented sources. If discussing with a partner, clarify that figures are subject to change.
Q: What’s the biggest mistake people make when creating a net worth statement?
Overvaluing assets and undervaluing liabilities. Common errors include:
- Listing a home at its "dream price" instead of market value
- Ignoring credit card debt or medical bills
- Assuming retirement accounts grow at unrealistic rates
