
Where It All Began
The Industrial Revolution didn’t just invent the steam engine; it created the first generation of engineers whose retirement security was tied to their employer’s longevity. Before the 1940s, most engineers—whether they designed bridges or refined oil—relied on savings accounts or modest annuities. Pensions were rare, and the idea of a "net worth" by retirement was almost nonexistent. Wealth accumulation was a slow burn, measured in land deeds and gold certificates rather than 401(k) balances. The turning point came with the post-WWII economic boom, when companies like General Electric and IBM began offering defined-benefit plans. Suddenly, an engineer’s average net worth by retirement wasn’t just a personal achievement; it was a corporate guarantee. The 1960s and 70s solidified this model. The rise of unionized engineering roles in aerospace and defense ensured that even mid-level technicians could retire with pensions that replaced 70% of their final salary. For the first time, an engineer’s financial future wasn’t a gamble—it was a contract. The average net worth of engineers by retirement age during this era hovered around $500,000 to $750,000 (adjusted for inflation), a figure that seemed untouchable. The system worked because it was designed to: employers bore the risk, and employees traded mobility for security.The Early Signs
Cracks began appearing in the 1980s, not from economic downturns but from a shift in corporate philosophy. Leveraged buyouts and the rise of shareholder capitalism turned pensions from a social contract into a liability. Companies like Kodak and Boeing—once bastions of engineering stability—began freezing pension plans, leaving long-tenured employees with IOUs instead of income. The average net worth of engineer by retirement age started to bifurcate: those who’d entered the workforce before 1980 saw their pensions protected; those who came after faced a new reality. The 1990s accelerated the trend. The dot-com crash and the subsequent layoffs in tech exposed another vulnerability: engineers in high-growth fields were now subject to the same volatility as their software counterparts. Startup culture, with its promise of equity and rapid exits, lured talent away from traditional firms—but the payoff was far from guaranteed. By the time the 2008 financial crisis hit, the average net worth of engineers by retirement had become a moving target. For those in legacy industries, it stagnated. For those in adaptive fields like renewable energy or biotech, it surged.The Turning Point
The inflection came in 2010, when two forces collided: the collapse of defined-benefit plans and the explosion of passive investing. The Pension Protection Act of 2006 had already shifted the burden onto employees, but the real change was cultural. Engineers who’d once seen their careers as linear paths now treated them as portfolios. The average net worth of engineer by retirement age stopped being a static number and became a function of adaptability."Engineering used to be a trade. Now it’s a series of bets—on industries, on skills, on when to cash out. The engineers who retire with $5 million didn’t just work harder; they treated their careers like venture capitalists treat startups." — Mark Reynolds, Partner at Bridgewater AssociatesThe shift wasn’t just about money. It was about mindset. The engineers who thrived were those who saw their technical expertise as a lever, not just a paycheck. Those who stayed in silos—specializing too early, refusing to pivot—found their average net worth by retirement shrinking relative to peers who’d diversified.

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1980–1990 | Pension freezes begin; 401(k)s replace defined-benefit plans. Engineers in legacy industries see stagnant growth in average net worth by retirement. |
| 1995–2005 | Tech boom creates high-paying roles in software-adjacent engineering. Early retirees in Silicon Valley see average net worth exceed $2M, but 2001 crash resets expectations. |
| 2008–2015 | Financial crisis forces layoffs; engineers in finance/quant roles suffer. Meanwhile, renewable energy and AI niches emerge, offering higher upside but greater risk. |
| 2016–2022 | Remote work and gig economy platforms (e.g., Upwork) allow engineers to freelance. Top 20% of earners see average net worth by retirement accelerate due to stock compensation and side income. |
| 2023–Present | AI and automation reshape demand; senior engineers in legacy fields face obsolescence risks. Early-career engineers prioritize equity and liquidity over stability. |
Lessons From the Journey
- Liquidity beats stability. Engineers who held cash or low-volatility assets during 2008–2009 saw their average net worth by retirement recover faster than those tied to employer stock.
- Geographic arbitrage matters. Cost-of-living adjustments can swing net worth by 30%+ over a career. A $150K salary in Austin delivers a different retirement outcome than the same salary in Boston.
- Side hustles compound. Engineers who monetized niche skills (e.g., patent consulting, online courses) added 20–40% to their average net worth without increasing base pay.
- Tax efficiency is non-negotiable. Those who maxed out HSAs, used Roth conversions strategically, and minimized capital gains taxes saw their effective net worth grow 1.5–2x faster.
- Networks create options. Engineers with alumni ties to VC firms or private equity had access to early-stage deals that diversified their portfolios beyond public markets.
Where Things Stand Today
Today, the average net worth of engineer by retirement age is less a single number and more a distribution. At the low end, engineers in traditional manufacturing or government roles retire with $600,000–$900,000, often reliant on Social Security and modest pensions. At the high end, those in tech, finance, or entrepreneurship hit $3M–$10M+, with portfolios heavy in private equity, real estate, and illiquid assets. The median? Around $1.5M, but the variance is widening. What’s changed isn’t just the figures—it’s the assumptions. Retirement planning used to be about replacing income. Now, it’s about preserving purchasing power in an era of inflation, longevity risk, and unpredictable markets. The engineers who’ll thrive are those who treat retirement as a dynamic phase, not a finish line.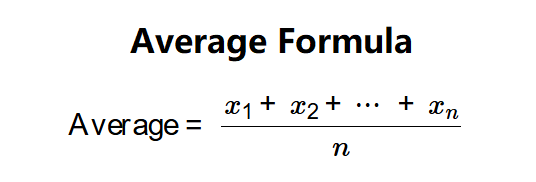
Conclusion
The story of the average net worth of engineer by retirement age is a microcosm of broader economic shifts. What was once a predictable arc has become a series of choices—some forced by industry trends, others self-inflicted. The engineers who retire with $500K did so by playing by old rules. Those who hit $5M did so by rewriting them. The lesson isn’t to chase the top percentile. It’s to recognize that engineering, like any profession, has become a financial ecosystem. The tools exist—tax-efficient strategies, alternative income streams, adaptive skill sets—but the discipline to use them separates the retirees with options from those with regrets.Comprehensive FAQs
Q: What’s the biggest mistake engineers make when planning for retirement?
Assuming their employer’s stability will last. Relying solely on a single company’s pension or stock compensation—without diversifying—has derailed more retirement plans than poor market timing. The average net worth of engineer by retirement age for those who bet everything on one employer is often 30–50% lower than peers who hedged.
Q: Can freelance engineers retire earlier than traditional employees?
Yes, but it depends on cash flow management. Freelancers in high-margin niches (e.g., AI consulting, embedded systems) can retire in their 40s or early 50s if they reinvest 60–70% of profits into low-volatility assets. However, the average net worth by retirement for freelancers tends to be lumpy—early retirees often see smaller balances than those who stayed in corporate roles but benefited from employer matches and pensions.
Q: How does location affect an engineer’s retirement net worth?
Dramatically. An engineer earning $180K in San Francisco will have a net worth by retirement that’s 40–50% lower than a peer earning the same salary in Dallas, due to housing costs, taxes, and opportunity costs (e.g., delayed retirement savings). Coastal cities offer higher salaries but erode wealth through lifestyle inflation and higher fees (e.g., private school tuitions, healthcare premiums).
Q: Are there engineering specialties that consistently outperform in retirement wealth?
Historically, yes. Fields like semiconductor design, quantitative finance, and renewable energy infrastructure have delivered above-average average net worth by retirement due to high salaries, equity compensation, and industry tailwinds. However, the gap narrows after age 50, as seniority in niche fields can sometimes limit mobility. Mechanical and civil engineers, while stable, often see lower retirement balances unless they pivot into management or consulting.
Q: What’s the most underrated factor in engineering retirement wealth?
Healthcare costs. While most discussions focus on 401(k) balances or real estate, the average net worth by retirement for engineers is often slashed by unplanned medical expenses. Those who max out HSAs, negotiate lower premiums through employer plans, or invest in long-term care insurance can preserve 15–25% more of their portfolio. Ignoring this is like assuming your car will never need repairs—eventually, the math catches up.
Q: Can an engineer with a $1M net worth at 50 retire comfortably?
It depends on the withdrawal rate and geographic needs. A $1M portfolio in a low-cost area (e.g., Midwest) with a 3% withdrawal rate could sustain $30K/year indefinitely. But in high-cost regions (e.g., NYC, SF), the same portfolio might require a 4–5% withdrawal rate, increasing the risk of depletion. The average net worth by retirement for engineers who retire at 50 is often higher than those who wait, but the trade-off is reduced Social Security benefits and longer exposure to market risk.
Q: How has AI changed the trajectory of engineering retirement wealth?
AI has created two opposing effects. For engineers in AI-adjacent roles (e.g., ML infrastructure, robotics), salaries and equity upside have surged, pushing up the average net worth by retirement. For those in automated or obsolete fields (e.g., traditional CAD drafting, legacy manufacturing), the risk of career stagnation or layoffs has increased. The net result? A sharper divide between early adopters and latecomers.
