
The Complete Overview of the Average Net Worth at 55
The concept of average net worth at 55 serves as a financial benchmark, but its true value lies in what it obscures. Surface-level figures mask critical variables: the homeowner’s mortgage-free equity versus the renter’s liquid savings, the doctor’s six-figure salary versus the gig worker’s irregular income. Even within the same country, regional disparities skew the average—someone in San Francisco’s tech hub might see their net worth balloon from stock options, while a peer in Rust Belt Ohio could struggle with stagnant wages. The number also ignores timing: those who bought homes in the 2012 dip benefited from a decade of appreciation, while latecomers to the market now face unaffordable price tags. What’s often overlooked is the psychological weight of this milestone. For many, turning 55 marks the first time they’re forced to confront retirement in tangible terms—no longer a distant abstraction but a looming deadline. The average net worth at this stage becomes a stress test: Can they maintain their lifestyle? Will they need to work longer? The answer depends less on raw numbers and more on asset allocation strategies, healthcare costs, and whether they’ve accounted for longevity risk. Even the wealthiest among them may find their portfolios vulnerable to sequence-of-returns risk—a bad market year at 55 can derail a carefully planned exit strategy.Historical Background and Evolution
The trajectory of the average net worth at 55 has been shaped by three seismic economic shifts. The first came in the 1980s, when deregulation and the rise of index funds democratized investing—though primarily for those with employer-sponsored plans. Before then, wealth accumulation relied on employer pensions or real estate, leaving most workers at the mercy of institutional gatekeepers. The second turning point arrived in 2000, when the dot-com bubble burst and home prices briefly dipped, offering a rare buying opportunity. Those who leveraged up in 2002–2007 saw their net worths inflate by the time they hit 55, while others who borrowed heavily against their homes faced foreclosure during the 2008 crisis. The third act began in 2020, when pandemic-era stimulus and remote-work flexibility created a bifurcated market. Tech workers and skilled tradespeople saw their net worths surge from stock market gains and home equity, while service-sector employees—disproportionately women and minorities—faced job losses and eroded savings. The result? A widening chasm in the average net worth at 55, where the top quintile’s figures now resemble the bottom quintile’s aspirations. Historically, wealth at this age was tied to tenure; today, it’s as much about asset class exposure as it is about years on the job.Core Mechanisms: How It Works
The average net worth at 55 isn’t a static number—it’s the cumulative result of three interlocking factors: income accumulation, debt management, and asset appreciation. Take a physician in their mid-50s: their salary peaks around this time, but student loans or malpractice insurance may drag down their net worth. Meanwhile, a plumber with the same age might own their home outright, have minimal debt, and see their net worth reflect decades of compounded savings. The difference lies in how each person navigated liquidity vs. leverage—the plumber’s equity is illiquid but stable, while the doctor’s high-earning years might be offset by lifestyle inflation. Tax policy plays an invisible but critical role. The 2017 Tax Cuts and Jobs Act lowered capital gains rates, benefiting those with significant stock portfolios, while the phase-out of the Stretch IRA in 2020 forced heirs to liquidate inherited assets faster—accelerating wealth transfer but often at a tax penalty. Even Social Security benefits, which kick in at 62, become a wildcard: claiming early reduces monthly payouts but can boost the average net worth at 55 by allowing earlier retirement. The mechanics are less about raw earning power and more about how each dollar is deployed—whether into appreciating assets, tax-advantaged accounts, or consumption.Key Benefits and Crucial Impact
The average net worth at 55 isn’t just a personal metric—it’s a leading indicator of economic health. Countries where this figure rises steadily tend to have stronger retirement systems, lower poverty rates among seniors, and more intergenerational wealth transfer. In the U.S., for example, the median net worth at 55 has grown by roughly 50% since 2000 (adjusted for inflation), though the gains are concentrated in the top 20%. The impact ripples outward: households with higher net worth at this stage are more likely to help adult children with down payments, fund care for aging parents, or weather unexpected medical bills without selling assets. Yet the benefits come with caveats. A high average net worth at 55 can create behavioral blind spots—overconfidence in market timing, underestimating healthcare costs, or assuming Social Security will cover gaps. The data shows that even affluent retirees often miscalculate how long their savings will last, with roughly 40% of those with $500,000+ in assets facing shortfalls by age 75. The crux lies in the transition from accumulation to preservation: the rules change at 55, and what worked for building wealth may backfire when drawing it down."Net worth at 55 isn’t about the number—it’s about the flexibility that number buys you. But flexibility is a double-edged sword: it lets you retire early, or it forces you to work longer because you misjudged inflation." — Karen Wambach, CFP and author of The 55-Plan
Major Advantages
- Financial independence threshold: Most experts consider $1 million in net worth at 55 a baseline for sustainable retirement, though this varies by location (e.g., $750K may suffice in the Midwest, $1.5M+ in coastal cities).
- Leverage for legacy planning: Those with significant net worth at this stage can structure trusts, life insurance policies, or charitable giving to minimize estate taxes while ensuring heirs benefit.
- Healthcare cost buffer: A net worth of $500K+ at 55 typically covers long-term care insurance premiums and out-of-pocket medical expenses without dipping into principal.
- Market timing advantage: Historically, retirees who hold assets through downturns (e.g., 2008, 2022) see their net worth rebound faster due to compounding—though this requires discipline.
- Negotiating power: High net worth at 55 can mean better terms on reverse mortgages, annuity rates, or even early retirement packages from employers.

Comparative Analysis
| Factor | Impact on Average Net Worth at 55 |
|---|---|
| Geographic Location | Urban centers (e.g., NYC, SF) see higher averages due to asset appreciation but also higher living costs. Rural areas may have lower figures but lower expenses. |
| Career Path | Professionals in tech, medicine, or law often exceed averages, while service-sector workers lag—though skilled tradespeople with homeownership can close the gap. |
| Marital Status | Married couples typically have 2–3x the net worth of singles at 55, thanks to pooled resources, spousal benefits, and shared real estate. |
| Economic Shocks | Those who owned homes in 2008 or invested in 2020–2021 saw net worths inflated by market recovery; others who borrowed heavily during these periods may still be repaying. |
Future Trends and Innovations
The average net worth at 55 is poised for disruption from two opposing forces: automation-driven wage stagnation and asset inflation. On one hand, AI and remote work may compress salaries for white-collar jobs, pressuring net worth growth unless workers pivot to high-margin gigs or side hustles. On the other, housing costs and healthcare expenses are outpacing wage growth, forcing mid-career professionals to adopt non-traditional strategies—like renting out spare rooms, monetizing hobbies, or delaying retirement to access pension benefits. The result? A bifurcation where early retirees with substantial net worths thrive, while others face forced part-time work well into their 70s. Innovations like cash-value life insurance policies and robo-advisors for retirement drawdowns are already reshaping how people manage their average net worth at 55. But the biggest wildcard remains policy shifts: changes to Social Security eligibility, capital gains taxes, or Medicare premiums could redefine what’s considered a "safe" net worth at this age. One thing is certain—passive accumulation (saving and investing) won’t suffice. The next generation at 55 will need to actively optimize their portfolios for inflation, longevity, and unexpected risks.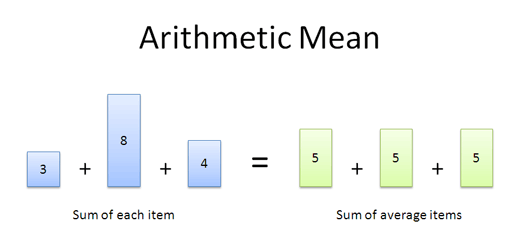
Conclusion
The average net worth at 55 is less about the number itself and more about the narrative it tells. It reflects not just financial acumen but resilience—navigating recessions, career pivots, and personal crises while building something sustainable. For some, it’s a trophy; for others, a warning. What’s clear is that the old playbook—save aggressively, retire at 65—no longer applies. The new reality demands flexibility, adaptive strategies, and a willingness to challenge assumptions about what retirement even looks like. The most successful approaches blend traditional wisdom (diversified portfolios, tax efficiency) with modern pragmatism (side income, flexible housing). The average net worth at 55 won’t save you from bad luck, but it can buy time—time to recover from setbacks, time to experiment with semi-retirement, or time to leave a legacy. The question isn’t whether you’ve hit the "right" number, but whether you’ve built a system that can weather whatever comes next.Comprehensive FAQs
Q: How does the average net worth at 55 compare between men and women?
A: Studies consistently show a gender wealth gap at this age, with men averaging 30–50% more than women due to factors like career interruptions for childcare, lower salaries in female-dominated fields, and longer lifespans requiring larger retirement buffers. The gap narrows slightly for same-sex couples but persists for heterosexual pairs, where women often handle unpaid caregiving roles.
Q: Can someone with an average net worth at 55 retire comfortably?
A: It depends on the 4% rule (annual withdrawal rate) and local costs. A $1M net worth might support a $40K/year lifestyle in a low-cost area but only $25K in a high-tax state like California. Many retirees underestimate healthcare costs (Medicare doesn’t cover everything) or sequence-of-returns risk. A safer target is $1.5M+ for most regions, though part-time work or downsizing can extend runway.
Q: How do student loans affect the average net worth at 55?
A: Student debt is the Achilles’ heel of net worth at this age. Borrowers with balances over $50K at 55 often see their net worth 15–20% lower than peers with no debt, due to delayed homeownership, lower retirement contributions, and higher stress-related spending. Public Service Loan Forgiveness or income-driven repayment plans can help, but many still face penalties in retirement.
Q: Does homeownership significantly boost the average net worth at 55?
A: Yes—homeowners at 55 typically have 4–5x the net worth of renters, thanks to equity buildup and mortgage paydown. However, the benefit varies by market: those who bought in 2000–2006 saw home values stagnate post-2008, while recent buyers in overheated markets may face negative equity if prices dip. Renting can be smarter in high-cost cities where rental yields exceed mortgage savings.
Q: How does divorce impact the average net worth at 55?
A: Divorce halves or worse the average net worth at 55 for women, who receive only 10–20% of marital assets in most cases. Men’s net worths drop by 25–40% due to legal fees and alimony/spousal support. Rebuilding takes 7–10 years, often requiring delayed retirement or reduced lifestyle expectations. Prenuptial agreements and equitable division laws vary by state, making legal strategy critical.
Q: What’s the biggest mistake people make with their average net worth at 55?
A: Overestimating Social Security benefits and underestimating longevity. Many assume they’ll claim at 62 for early payouts, only to realize they’ve locked in reduced benefits for life. Others fail to account for 20+ years in retirement, leading to asset depletion. The fix? Delay claiming Social Security until 70 (if possible) and use the 4% rule with adjustments for inflation and healthcare inflation.
Q: Can someone increase their average net worth at 55 after 55?
A: Absolutely—but the strategies shift. High-income earners can max out HSAs, contribute to backdoor Roth IRAs, or pursue consulting gigs. Homeowners might rent out spare rooms or downsize to unlock equity. Investors should shift to bond-heavy portfolios (60/40 or 70/30) to preserve capital. The key is reducing risk exposure while maintaining liquidity for unexpected expenses.
