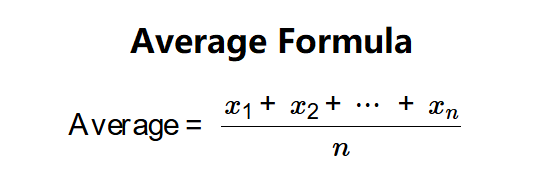The
average net worth of all households USA is a barometer of economic health, but the numbers tell a story far more complex than a single statistic. As of recent data, the median household net worth—where half of households fall above and half below—stands at roughly $120,000, while the mean (average) hovers near $130,000, inflated by the ultra-wealthy. This gap exposes a critical truth: wealth in America is not evenly distributed. The top 10% of households hold nearly 70% of all liquid assets, leaving the majority struggling with stagnant wages, rising costs, and the lingering effects of past recessions. Yet, these figures obscure regional disparities: a suburban family in Texas may have a net worth triple that of a urban renter in New York, even with similar incomes.
The
average net worth of all households USA is also a moving target, shaped by cycles of inflation, stock market performance, and policy shifts. The Federal Reserve’s triennial Survey of Consumer Finances remains the gold standard for these measurements, but its lag—data often reflects the prior year—means real-time trends are speculative. For instance, the 2022 report showed a 12% decline in median net worth for Black households compared to 2019, while white households saw a 3% increase. Such shifts underscore how systemic barriers—discriminatory lending, wage gaps, and asset stripping—distort the narrative of collective prosperity.
Behind the averages lie generational divides. Millennials, now the largest generation in the workforce, entered adulthood during the 2008 financial crisis, delaying homeownership and retirement savings. Their
average net worth of all households USA in their 40s lags behind Gen X by $60,000, according to Federal Reserve estimates. Meanwhile, Baby Boomers—who benefited from rising home values and stock market growth—hold the lion’s share of wealth, with 60% of households aged 65+ owning their homes outright. This concentration of assets raises questions: Is wealth truly mobile across generations, or is America’s middle class perpetually at risk of being priced out?

The
average net worth of all households USA is also a reflection of structural inequities. Homeownership remains the single largest driver of wealth accumulation, yet Black and Hispanic households are half as likely to own a home as white households, per Pew Research. Student debt, now exceeding $1.7 trillion, further suppresses net worth for younger cohorts, while older Americans leverage home equity to fund retirement. The result? A wealth pyramid where the base is precarious, and the apex grows wider with each market uptick.
The Short Answers
- The average net worth of all households USA (mean) is estimated at $130,000, but the median sits closer to $120,000.
- Wealth inequality is extreme: the top 1% holds 35% of all household wealth, while the bottom 50% holds just 2.6%.
- Homeownership accounts for 67% of total household net worth, making housing the primary wealth-building tool.
- Generational wealth gaps persist—Gen X leads in net worth, while Millennials trail due to economic headwinds.
- The average net worth of all households USA varies wildly by race, with white households holding $188,200 vs. $36,100 for Black households.
Deep Dive: The Full Picture
The
average net worth of all households USA is a composite of assets—cash, investments, real estate—and liabilities, from mortgages to student loans. Yet, this snapshot masks volatility. The 2020 pandemic-induced recession saw median net worth drop $3,000 in a single year, only to rebound as stock markets surged. The recovery was uneven: households earning over $100,000 saw net worth grow by $50,000, while those earning under $50,000 gained just $3,000. This disparity highlights how financial resilience is tied to income brackets, not just economic growth.
The
average net worth of all households USA also reflects geographic disparities. Coastal states like California and New York boast higher median incomes but lower median net worth due to exorbitant housing costs. In contrast, states like Iowa and South Dakota, where homeownership rates exceed 75%, see net worth figures 20% higher than the national average. Even within cities, neighborhoods segmented by race and income reveal stark divides: a $200,000 home in a majority-white suburb may yield $100,000 in equity, while an identical property in a predominantly Black neighborhood could hold $50,000 due to historical redlining and lower appraisals.
####
The Context You Need
Understanding the
average net worth of all households USA requires grasping the role of policy. The Tax Cuts and Jobs Act of 2017 temporarily boosted take-home pay but did little to address wealth accumulation for low- and middle-income families. Meanwhile, the Homeowners Protection Act and FHA loan programs have expanded access to homeownership, though discriminatory lending practices persist. The Federal Reserve’s balance sheet expansion post-2008—pumping trillions into the economy—lifted asset prices, benefiting those already invested in stocks and real estate.
Demographics also reshape the
average net worth of all households USA. Single-person households, now 28% of all U.S. homes, have a median net worth of $62,000—half that of married couples. Divorce, delayed marriages, and rising singlehood rates further fragment wealth. Immigrant households, despite lower median incomes, often build net worth faster due to higher labor force participation and entrepreneurial activity. Yet, language barriers and unequal access to credit can offset these advantages.
####
The Mechanics
The average net worth of all households USA is driven by three pillars: earned income, asset appreciation, and inheritance. Earned income is the foundation, but without savings or investments, wages alone rarely build generational wealth. Asset appreciation—stocks, real estate, and retirement accounts—amplifies net worth, but participation in these markets is skewed. Only 56% of Americans own stocks, and just 30% have retirement accounts, per the Fed. Inheritance, the third leg, is the most unequal: 70% of estates are passed down to heirs, but only 10% of households receive any inheritance at all.
Tax policy distorts these mechanics. Capital gains taxes favor long-term investors, while estate taxes hit only the top 0.2% of households. The result? Wealth compounds for those who already have it. A $1 million portfolio growing at 7% annually becomes $2.7 million in 20 years—assuming no withdrawals. For a household with $50,000 in savings, the same growth yields $170,000. The math is simple: time and scale favor the wealthy.
Details That Change the Picture
The average net worth of all households USA is often misrepresented by focusing solely on the mean, which skews upward due to billionaires and corporate wealth. The median—a better measure of typical households—paints a bleaker picture. In 2022, the median net worth for white households was $188,200, compared to $36,100 for Black households and $72,000 for Hispanic households. These gaps persist even after controlling for income, education, and homeownership rates, pointing to systemic exclusion rather than individual failure.

Regional data further complicates the narrative. In Mississippi, the median net worth is $66,000, but 60% of households lack retirement savings. In New Jersey, the median is $810,000, yet 40% of renters spend over 30% of income on housing. The average net worth of all households USA is not a monolith; it’s a patchwork of local economies, policy decisions, and historical injustices.
> "Wealth is not just about money—it’s about access. If you’re born into a family that owns a home, has a college degree, and can pass down assets, you start the race ahead. If not, you’re playing catch-up in a system designed to keep you there."
> — Darrick Hamilton, economist and professor at The New School
| Factor | Impact on Net Worth |
|--------------------------|----------------------------------------------------------------------------------------|
| Homeownership | Adds $200,000+ in equity over 30 years vs. renting. |
| Student Debt | Reduces median net worth by $25,000 for borrowers under 40. |
| Retirement Accounts | Households with 401(k)s have $150,000 more in net worth than those without. |
| Inheritance | Receivers see net worth 3x higher than non-recipients. |
| Geography | Coastal states suppress net worth due to housing inflation; Midwest states benefit. |
Conclusion
The average net worth of all households USA is a reflection of America’s economic contradictions: a land of opportunity where opportunity is unevenly distributed. While the stock market’s recent highs have swollen the top percentiles, the median household remains vulnerable to shocks—rising rents, medical debt, or a single job loss. The data reveals not just financial disparities but structural failures: a tax code that rewards inheritance over labor, a housing market that excludes the poor, and a retirement system that leaves millions behind.
Addressing these imbalances requires more than policy tweaks—it demands a reckoning with history. Redlining, wage suppression, and predatory lending didn’t happen overnight, and their effects won’t vanish with a single reform. Yet, solutions exist: expanding the Child Tax Credit, reforming zoning laws to allow affordable housing, and ensuring universal access to financial literacy. The average net worth of all households USA won’t improve until wealth-building tools are democratized, not just for the fortunate few but for every family willing to work.
Comprehensive FAQs
#### Q: How often is the average net worth of all households USA updated?
A: The Federal Reserve’s Survey of Consumer Finances—the primary source—is released every three years, with the latest data covering 2022. For real-time trends, economists rely on quarterly reports from the Fed and Census Bureau, but these track income, not net worth.
#### Q: Does the average net worth of all households USA include debt?
A: Yes. Net worth is total assets minus total liabilities (mortgages, student loans, credit cards). A household with $500,000 in home equity but $300,000 in mortgage debt has a net worth of $200,000, not $500,000.
#### Q: Why is the average net worth of all households USA higher than the median?
A: The mean (average) is skewed by ultra-high-net-worth individuals (e.g., a single billionaire can inflate the average dramatically). The median (middle value) is a better measure of typical households, as it ignores outliers.
#### Q: How does student debt affect the average net worth of all households USA?
A: Student loan debt suppresses net worth by $25,000–$50,000 for borrowers under 40, per Fed data. Unlike mortgages, student loans don’t build equity, and default rates disproportionately affect Black and Hispanic borrowers.
#### Q: Can the average net worth of all households USA recover from a recession?
A: Historically, yes—but recovery is uneven. The 2008 crash saw median net worth drop 16%, but it took five years to return to pre-crisis levels. The 2020 pandemic dip was shorter (median fell $3,000), but low-income households saw no rebound by 2022.
#### Q: What’s the biggest factor increasing the average net worth of all households USA?
A: Homeownership. Homes account for 67% of total net worth, and homeowners have 12x the wealth of renters. Policies like down payment assistance and rent control could accelerate this trend for lower-income families.